Author: Ethan Miller

  • How HMRC Is Using AI to Spot Tax Dodgers, and Why Innocent Self-Employed Brits Are Getting Caught in the Net

    How HMRC Is Using AI to Spot Tax Dodgers, and Why Innocent Self-Employed Brits Are Getting Caught in the Net

    Something quietly changed at HMRC over the past few years. The letters landing on doormats across Britain, the ones asking pointed questions about your income, your expenses, your side hustle, didn’t always come from a human inspector who’d noticed something odd. Increasingly, they came from an algorithm. HMRC’s AI tax investigation tools have been expanding at pace, and while the Revenue insists they’re catching genuine fraud, a growing number of honest, self-employed people are finding themselves on the wrong end of an automated red flag they had absolutely no idea was coming.

    I’ve spoken to freelancers, sole traders and small business owners who describe the experience as bewildering. One graphic designer in Leeds received an inquiry letter asking her to explain a three-year discrepancy in her declared income that turned out to be entirely down to a legitimate bad year followed by a very good one. Another, a self-employed plumber in Bristol, was flagged for having expenses that looked “anomalous” compared to others in his sector. Both cases were eventually resolved in the taxpayers’ favour. Both still caused months of stress and professional fees for an accountant to sort out.
    Self-employed person reading an HMRC AI tax investigation letter at home
    Photo by Ron Lach on Pexels

    How HMRC’s AI compliance system actually works

    HMRC’s system is called Connect. It’s been running in some form since around 2010, but the machine learning capabilities layered on top have grown considerably. Connect pulls in data from an enormous range of sources: Companies House records, Land Registry, letting platforms, bank transaction data shared under international agreements, social media, online marketplaces like eBay and Vinted, and even information from the DVLA. It then cross-references all of that against what you’ve declared on your tax return.

    If the algorithm detects what it considers an inconsistency, that triggers a risk score. High enough score, and your file gets flagged for a compliance check, which can range from a simple nudge letter asking you to review your return, all the way up to a full formal investigation. HMRC processes around 300,000 compliance checks a year, and the proportion initiated by automated tools rather than human judgment has risen sharply. The Revenue doesn’t publish an exact figure for what percentage of flags are AI-generated, but tax professionals I’ve seen quoted in the trade press put the estimate well above half.

    Why false positives happen more than you’d think

    The problem with any algorithm built to detect outliers is that genuine outliers exist. A musician who earned £8,000 in 2023 and £47,000 in 2025 because they finally got a sync deal is going to look suspicious to a system trained on smooth income curves. A childminder who suddenly has very low declared income one year because she took maternity leave is going to look like she’s hiding earnings. The system is good at spotting patterns. It’s not good at understanding context.

    There’s also a data quality problem. Connect is only as reliable as the information fed into it. If a third-party platform reports your earnings incorrectly, or if a previous employer files a P60 with an error, that discrepancy goes into the system as a potential problem with your return. You might not even know the wrong data exists until the investigation letter arrives.
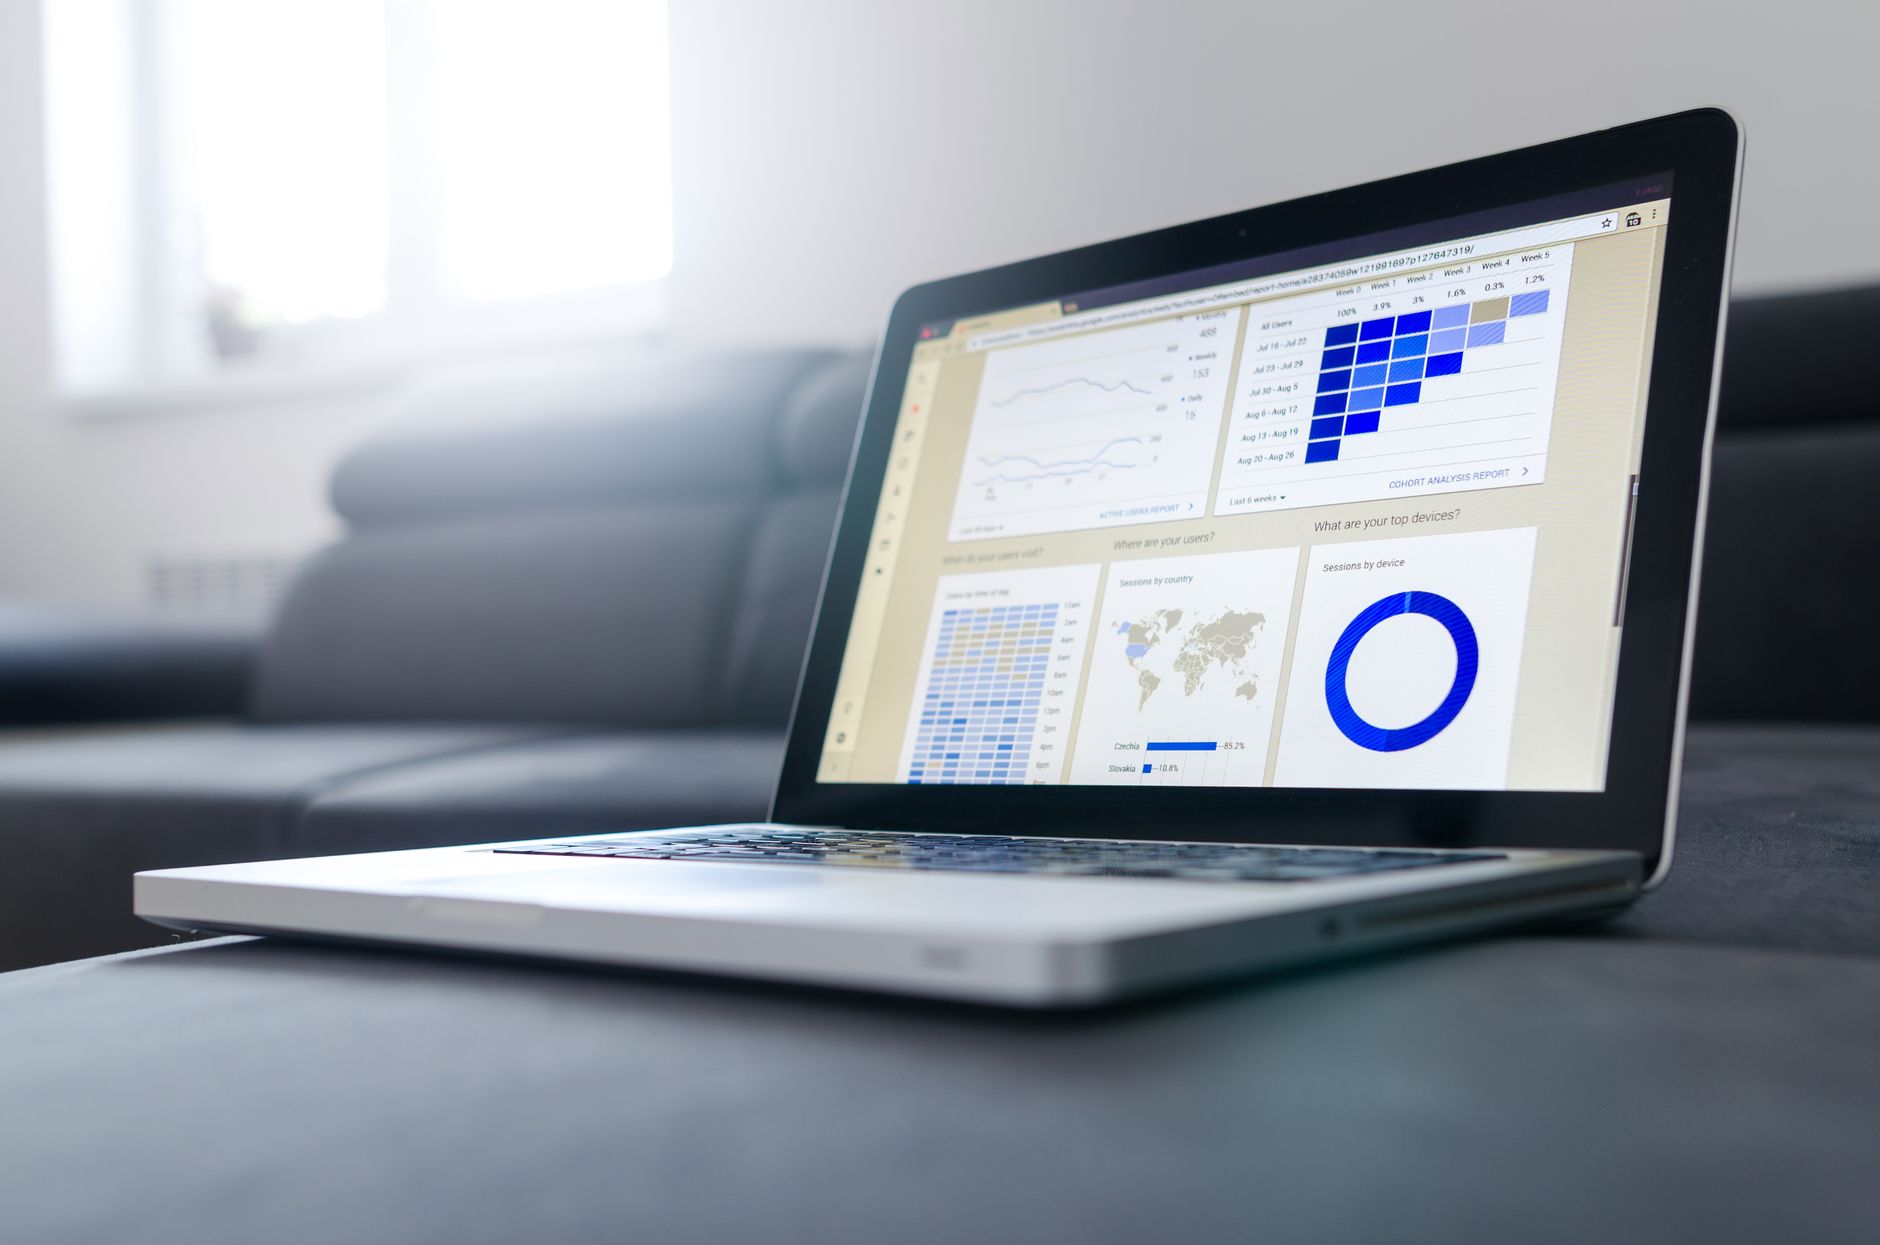
    HMRC AI tax investigation data analytics dashboard showing income pattern analysis
    Photo by Lukas Blazek on Pexels

    Tax adviser groups including the Low Incomes Tax Reform Group have been raising concerns about this for several years. Their research consistently shows that lower-income self-employed people, who are less likely to have professional accountants and more likely to make innocent record-keeping errors, are disproportionately affected by automated compliance activity. You can read more about their work at litrg.org.uk, and I’d genuinely recommend it if you’re self-employed and feeling confused about your obligations.

    What rights do you have if HMRC flags you?

    Here’s the bit that most people don’t know, and it matters. Being flagged by HMRC’s system does not mean you’ve done anything wrong, and you have meaningful rights throughout any compliance process.

    First: you do not have to respond to an informal nudge letter by simply agreeing with whatever HMRC suggests. These letters often invite you to “consider whether your return is correct” and to make a voluntary amendment if you think there’s been an error. If your return was correct, you can say so, clearly, in writing.

    Second: if HMRC opens a formal inquiry under Section 9A of the Taxes Management Act 1970, you have the right to know what they’re looking at, to be represented by an accountant or tax adviser, and to challenge their conclusions at a Tax Tribunal if you believe they’re wrong. The process is adversarial in the legal sense, meaning HMRC has to make their case, not just assert it.

    Third: if the investigation finds nothing wrong, you can claim some of your professional costs back in certain circumstances, though this is unfortunately not automatic and requires a formal claim.

    The general advice from tax professionals is: don’t panic, don’t ignore it, and get professional help early. The longer an inquiry runs without a clear response, the more complicated it tends to become.

    The gig economy is particularly exposed

    If you’re earning money through platforms, whether that’s driving for a delivery service, selling crafts on Etsy, renting a room through a lettings app, or doing shifts through a care agency app, you’re in a category HMRC is paying very close attention to. The Digital Platforms reporting rules, which came into force at the start of 2025, now require UK-based platforms to report user earnings directly to HMRC annually. That’s a huge amount of new data flowing into Connect, and a lot of people who’ve been quietly earning below what they assumed were reporting thresholds are about to find out that HMRC knows more than they did.

    This is also where the line between innocent confusion and actual avoidance can get genuinely blurry. Some people earn through multiple gig platforms simultaneously and simply don’t realise the combined total tips them over the Self Assessment threshold. The AI doesn’t know whether your ignorance was deliberate. It just knows the numbers don’t match.

    If you’re ever trying to make sense of whether a contact from HMRC is legitimate or part of a wider pattern of suspicious official-looking communications, it’s worth checking resources like 0lly.uk which covers this sort of thing in detail. Fake HMRC phishing letters are unfortunately common, and distinguishing them from genuine compliance correspondence is a skill worth having.

    The rise of AI in tax compliance is, on balance, probably a good thing for catching serious fraud. But the cost of that efficiency, measured in stress, accountancy bills and wasted hours for people who did nothing wrong, deserves more public scrutiny than it currently gets. If you’re self-employed, keep your records clean, understand your obligations, and don’t assume that a clean conscience means you’re immune to an automated flag. The algorithm doesn’t care about your intentions. It just cares about the numbers.

    For anyone who’s curious about how much of their financial life is now being quietly tracked and cross-referenced, the piece we did on subscription costs Brits don’t realise they’re paying touches on just how many platforms are now sharing data with regulators. And if you’ve ever wondered how far automated systems can reach into everyday working life, the article on AI screening tools used by UK employers is a useful companion read. Algorithms are everywhere now. HMRC’s version just has particularly sharp teeth.

    Frequently Asked Questions

    How does HMRC decide who to investigate for tax compliance?

    HMRC uses a system called Connect, which pulls data from Companies House, Land Registry, online platforms, banks and other sources and compares it against your declared income. If the algorithm detects what it considers an inconsistency, it generates a risk score. High-risk cases are flagged for a compliance check, which may be handled automatically or passed to a human inspector.

    What happens if HMRC sends me a compliance check letter?

    Don’t ignore it and don’t automatically agree with whatever the letter implies. If it’s an informal nudge, you can respond in writing confirming your return is correct. If it’s a formal inquiry under Section 9A of the Taxes Management Act, you have the right to professional representation and to challenge HMRC’s conclusions at a Tax Tribunal if needed.

    Can HMRC see my earnings from gig economy platforms like Deliveroo or Etsy?

    Yes. Digital Platforms reporting rules introduced in early 2025 require UK-based platforms to report user earnings to HMRC directly each year. This means income from delivery work, craft sales, room rentals and similar sources is now automatically shared with HMRC and fed into their compliance system.

    What is a false positive in an HMRC AI investigation?

    A false positive is when HMRC’s algorithm flags someone for investigation who has actually done nothing wrong. This happens when legitimate income patterns, like a bad year followed by a very good one, or a career break, look statistically unusual to the system. HMRC doesn’t publish figures on how often this occurs, but tax professionals estimate it’s common among lower-income self-employed workers.

    Can I claim my accountancy costs back if HMRC investigates me and finds nothing?

    In some circumstances, yes. If HMRC opens a formal inquiry and closes it without finding any underpayment, you may be able to claim professional costs through a formal application. This isn’t automatic, so you’d need to raise it explicitly. Tax investigation insurance, which many accountants offer as an add-on, is worth considering before any inquiry begins.
  • Inside the FCA’s Quiet War on ‘Finfluencers’, and Why Young Brits Are Still Taking Financial Advice From Instagram

    Inside the FCA’s Quiet War on ‘Finfluencers’, and Why Young Brits Are Still Taking Financial Advice From Instagram

    There’s a version of financial advice that arrives at 11pm, soundtracked by lo-fi beats, delivered by someone in a Porsche they may or may not own. It tells you which crypto to buy, which ISA is “actually worth it”, and why your pension fund manager is secretly robbing you. It gets 400,000 views. The person giving it has no licence, no qualifications, and possibly no real portfolio. Welcome to the world of the finfluencer, and welcome to the FCA’s biggest headache right now.

    Finfluencer regulation in the UK, and the FCA’s attempts to enforce it, have become one of the more fascinating cat-and-mouse stories in British finance. The rules exist. The watchdog has teeth. And yet the unlicensed advice keeps flowing, the follower counts keep climbing, and young Brits keep acting on tips that could genuinely cost them serious money.

    Young man scrolling social media financial content — finfluencer regulation UK FCA
    Photo by cottonbro studio on Pexels

    What the FCA actually says about financial promotions on social media

    The Financial Conduct Authority updated its financial promotions rules in October 2023, and the changes were significant. Any communication that constitutes a “financial promotion”, broadly, anything that invites someone to engage with a financial product or service, must either be made by an FCA-authorised person or approved by one. That covers Instagram Reels, TikTok videos, YouTube “portfolio update” videos, the lot.

    The FCA has been explicit: finfluencers operating without authorisation are breaking the law. The regulator published a dedicated finfluencer guidance page and has made clear that prison sentences of up to two years, or unlimited fines, are on the table. In 2024, the FCA referred nine finfluencers to the Crown Prosecution Service, including some with substantial followings. By early 2026, several cases have resulted in prosecutions. That sounds decisive. So why does opening Instagram on any given Tuesday still feel like scrolling through an unlicensed trading floor?

    Why enforcement is so genuinely difficult

    I’ve spent a fair bit of time looking at how the FCA’s enforcement operation actually works, and the honest answer is: it’s chasing a fog. The scale is the first problem. Ofcom’s own research suggests around 70% of 18-to-24-year-olds in the UK have seen financial content on social media they couldn’t verify was legitimate. That’s millions of pieces of content, produced faster than any team of investigators can review them.

    Jurisdiction is the second problem. A finfluencer based in Dubai, pushing content to a British audience via a UK-registered account, is simultaneously everywhere and nowhere. The FCA can write to the platform. The platform may or may not act. The influencer has usually moved to a new account, a new platform, or a new structure, perhaps a Cayman Islands LLC selling “educational content” that just happens to recommend specific assets.

    The third problem is the content itself. The most legally savvy finfluencers have got remarkably good at skirting the line. “This is not financial advice” in the caption. A question format rather than a recommendation. “I’m just sharing what I personally do” as a shield against the promotions rules. None of that actually changes the legal position, if it functions as a financial promotion, it’s regulated as one, but it makes the FCA’s job of building a clear-cut case considerably harder.

    Investment charts on a laptop screen illustrating finfluencer regulation UK FCA concerns
    Photo by Leeloo The First on Pexels

    The real risk for young Brits following finfluencer advice

    The FCA’s Financial Lives survey, last updated in 2024, found that nearly half of UK adults aged 18 to 34 say social media has influenced at least one financial decision they’ve made. That’s a remarkable figure. Some of those decisions were harmless, switching to a better-rate savings account after seeing a comparison video. Others were considerably less so.

    I’d argue the biggest risk isn’t the obvious scam. It’s the plausible-sounding advice that’s just wrong for your circumstances, delivered with total confidence by someone who genuinely believes what they’re saying. An influencer with 300,000 followers who enthuses about leveraged ETFs isn’t necessarily malicious, they might just be catastrophically unqualified to be talking about leveraged ETFs to people who’ve never invested before. The FCA distinguishes between “generic financial education” and advice that’s specific enough to constitute a promotion, but that line is blurry in practice and almost invisible to a 22-year-old watching a video on the bus.

    Crypto is the sharpest end of this. Several high-profile cases in 2024 and 2025 involved influencers promoting tokens that collapsed shortly after their posts, a pattern the FCA has described as consistent with pump-and-dump manipulation. Young investors who bought in lost money they couldn’t afford. The influencer deleted the posts. Almost nobody got their money back.

    How finfluencers actually build their reach, and who profits

    Understanding the mechanics helps explain why the problem is so sticky. Finfluencers, like any content creator in 2026, rely on link infrastructure as much as content. A single social media bio link routes followers to a landing page covering everything from affiliate product links to paid courses to referral sign-ups for trading apps. Social media influencers trying to manage that kind of multi-link presence often use a link-in-bio tool to create a quick landing page that centralises all their offerings. LinkVine, a UK-based link manager that lets social media creators manage their links from one place, is one example of how to manage your links across multiple platforms cleanly, their free tier (available at linkvine.uk) is popular with smaller creators who need a tidy quick landing page without the cost. The point is that the commercial engine behind a finfluencer account is often more layered than it appears, with affiliate commissions from trading platforms sitting quietly behind what looks like a helpful comparison video.

    That affiliate model matters for regulation because the FCA’s rules cover paid promotions explicitly. If a finfluencer earns commission every time someone signs up to a trading app via their link, that relationship has to be disclosed, and if the app isn’t FCA-authorised, the whole arrangement is potentially illegal regardless of any disclosures. The ASA (Advertising Standards Authority) has run its own parallel enforcement on undisclosed paid partnerships, adding another layer of scrutiny that some creators are only now becoming aware of.

    What the FCA should probably do next

    My take: the FCA’s current approach is necessary but not sufficient. Prosecuting individual finfluencers is useful for deterrence, but the regulator’s real leverage is with the platforms. TikTok, Instagram, and YouTube have more practical ability to prevent unlicensed financial promotions reaching UK users than any regulator does, and the Online Safety Act, which Ofcom is now actively enforcing, gives the FCA a potential ally in pushing platforms to act. Coordinated pressure between the two regulators would be considerably more effective than the FCA going it alone.

    There’s also a consumer education angle that’s being underused. The FCA’s InvestSmart campaign is decent, but it’s not reaching people where finfluencers reach them. Shorter, sharper content on the same platforms, explaining what “FCA-authorised” actually means and why it matters, would help. Some of Britain’s youngest content creators are already savvy enough to build compliant financial content, amplifying those voices would be a good start.

    The broader context is that young Brits are genuinely hungry for financial information, and the traditional financial services industry has done a poor job of serving them in formats they actually use. Finfluencers filled a vacuum. The FCA’s job isn’t just to police the bad actors; it’s to help make sure better information gets through. That’s a bigger project than any prosecution, and it hasn’t really started yet.

    In the meantime: if someone on Instagram is telling you where to put your money, check the FCA Register before you move a penny. It takes about 45 seconds and it’s free. The Porsche can wait.

    Frequently Asked Questions

    What is a finfluencer and why is the FCA cracking down on them?

    A finfluencer is a social media creator who produces content about personal finance, investing, or trading, often on Instagram, TikTok, or YouTube. The FCA is cracking down because many operate without FCA authorisation, which means their financial promotions are technically illegal under the Financial Services and Markets Act 2000.

    Can a UK finfluencer be prosecuted for giving unlicensed financial advice?

    Yes. The FCA updated its financial promotions rules in October 2023 and has since referred multiple UK finfluencers to the Crown Prosecution Service. Penalties include unlimited fines and up to two years in prison. Simply adding ‘this is not financial advice’ to a post does not automatically make a promotion legal.

    How do I check if a financial influencer is FCA-authorised?

    You can search the FCA Register at register.fca.org.uk, it lists every firm and individual authorised to give financial advice or issue financial promotions in the UK. If the influencer isn’t on there and isn’t working with someone who is, treat their advice with serious caution.

    Why is finfluencer regulation UK FCA enforcement so slow?

    The volume of content is enormous, many creators operate from outside the UK, and the most legally cautious finfluencers frame their content as ‘education’ rather than advice. Building a prosecution-ready case is time-consuming, and platforms don’t always respond quickly to FCA requests to remove content.

    What should young investors do to protect themselves from bad finfluencer advice?

    Always check the FCA Register before acting on any financial tip. Look for disclosures about paid partnerships, and be particularly wary of crypto or high-risk investment content from unverified creators. The FCA’s InvestSmart campaign at fca.org.uk/investsmart offers free, impartial guidance on investing safely.

  • The UK Supermarkets Quietly Replacing Shelf Stackers With Robots, and Which Jobs Are Actually Safe

    The UK Supermarkets Quietly Replacing Shelf Stackers With Robots, and Which Jobs Are Actually Safe

    Something odd is happening in the cereal aisle. A squat, wheeled machine trundles past the Weetabix, pauses, scans a shelf, and logs a gap in the system before any human has even noticed. No tea break needed. No aching back. No overtime. Britain’s major supermarket chains are quietly rolling out supermarket shelf robots, and the conversation about what that means for hundreds of thousands of shop floor workers is only just getting started.

    Supermarket shelf robot scanning a grocery aisle in a UK store
    Photo by Jace Oner on Pexels

    Which supermarkets are actually trialling robots right now?

    Ocado is the obvious place to start, because it’s been the most aggressive. Its Erith and Andover customer fulfilment centres run on a grid of autonomous robots that pick and pack groceries at speeds no human team could match. That’s a slightly different use case to in-store shelf management, but the underlying logic is identical: automate the repetitive, physical stuff. Ocado’s technology arm, Ocado Solutions, has licensed this kit to Kroger in the US and Coles in Australia, so the appetite globally is clearly there.

    Tesco has been trialling shelf-scanning robots in a handful of stores since 2023, using technology from a company called Simbe Robotics. The robot, called Tally, rolls around the store capturing shelf data, identifying misplaced items and flagging stock-outs. Tesco frames it as a tool that helps staff rather than replaces them, which is a line I’ve heard enough times now to treat with a degree of scepticism. Sainsbury’s, meanwhile, has been quietly experimenting with automated inventory management in its distribution centres, and there are credible reports of in-store scanning pilots at a small number of larger-format shops.

    Morrisons has invested heavily in robotics at its Bradford distribution hub, and Marks and Spencer has tested automated picking in its Welham Green warehouse. Even Co-op, not typically the flashiest operator, has looked at autonomous stock-checking devices for its convenience stores.

    What the GMB union says, and why it’s more nuanced than you’d think

    The GMB union, which represents a large chunk of Britain’s supermarket workforce, hasn’t come out swinging against robots in quite the way you might expect. Their position is more measured, focused on consultation rights and transition support than outright opposition. In statements from 2025, the GMB called for meaningful negotiations before any deployment of automation that affects headcount, and for retraining guarantees to be built into any deal.

    That’s a pragmatic stance. The union knows full well that fighting technology is a losing battle; what matters is what happens to the people on the shop floor while it arrives. According to the ONS Labour Force Survey, retail is one of the largest employment sectors in the UK, with roughly 2.9 million people working in it. Even a modest automation of low-complexity tasks chips away at that figure over time.

    Automated warehouse robots used in supermarket shelf management and order fulfilment
    Photo by YIHAI LASER on Pexels

    Talking to workers informally (a couple of friends who stack shelves in a Tesco Extra and a Sainsbury’s in the South East), the reaction is mixed. One told me the scanning robot in their store is actually seen as a bit of a novelty, and that staff have started joking about giving it a name. The other was less amused, pointing out that their store has been running with fewer staff on the floor for two years now, and the robot feels like management’s justification for not hiring anyone new.

    What supermarket shelf robots actually do (and don’t do)

    It’s worth being precise here, because the technology varies significantly. The most common in-store robots don’t physically stack shelves at all. They scan them. They roll the aisles, capture images, detect gaps, identify price label errors and flag items in the wrong location. The data goes back to a management system, and a human then acts on it.

    True robotic shelf replenishment, where a machine physically picks a product from a trolley and places it on a shelf, is substantially harder to engineer reliably given the chaotic variety of product shapes and sizes. Some warehouse environments have cracked this for ambient goods, but the in-store version remains largely out of reach for now. That distinction matters enormously for the jobs conversation, because scanning robots and stacking robots are very different threats to different types of work.

    What’s more certain is the impact on back-of-store operations. Automated replenishment systems that manage ordering, stock rotation and delivery scheduling are already reducing the need for certain supervisory and administrative roles in large supermarkets. That’s the quieter, less visible job erosion that doesn’t make headlines.

    Are any jobs genuinely safe?

    Customer-facing roles feel reasonably secure for now, not because technology couldn’t eventually replace them but because supermarkets know that a human at the checkout or on the shop floor still genuinely matters to customer experience. Self-checkouts are a useful reference point: they’ve expanded massively, but most stores still employ people to oversee them, manage queues and handle the inevitable errors. Full automation of the customer interaction hasn’t happened, and there’s some commercial logic behind that.

    Deli counters, fresh produce advice, specialist departments, these remain firmly human. So do roles that require judgment, empathy or real-time problem-solving. A robot can’t deal with a customer who’s had a fall, or handle an aggressive shoplifter, or decide that a particular delivery of strawberries isn’t good enough to put out on the shelf.

    The roles under most pressure are the purely repetitive ones: systematic shelf scanning, overnight replenishment of identical SKUs, warehouse picking for standard grocery orders. These are the jobs where the business case for automation is clearest and the displacement timeline is shortest.

    The bigger picture for Britain’s workers

    This isn’t happening in isolation. Across the UK economy, automation is reshaping work in ways that are sometimes dramatic and sometimes barely perceptible. I’ve written before about how British landlords are using smart home tech to manage properties more efficiently, and how young entrepreneurs are building businesses entirely on their phones. The thread running through all of it is the same: technology doesn’t make jobs disappear overnight, but it shifts what skills are actually valuable.

    For supermarket workers, that probably means a gradual shift toward roles that require more customer interaction, more technical oversight of automated systems, and more flexibility. That’s not necessarily a disaster, but it does require investment in training that most retailers haven’t historically been brilliant at providing. The GMB’s push for retraining guarantees isn’t idealism; it’s the only practical way this transition doesn’t leave a large number of people behind.

    Interestingly, the same economic pressures driving supermarket automation are rippling through other sectors. In property management, for instance, companies like Lister Group are having to rethink how they deliver services as digital tools reshape client expectations. Automation anxiety isn’t unique to retail, it’s a conversation happening across every industry that employs people to do repeatable tasks.

    The robots in the cereal aisle aren’t going away. But how supermarkets handle the human side of this transition, whether with genuine consultation and support or with a press release about “empowering colleagues”, will tell us a lot about what kind of employers they actually are. I know which version I’m expecting. I’d genuinely love to be proved wrong.

    Frequently Asked Questions

    Which UK supermarkets are using shelf-stacking robots in 2026?

    Tesco has trialled Simbe Robotics’ Tally scanning robot in multiple stores, Ocado runs fully automated fulfilment centres, and Sainsbury’s and Morrisons have both piloted automated inventory systems in warehouses. Most in-store robots currently scan shelves rather than physically stack them.

    Do supermarket robots actually replace workers or just assist them?

    Currently, most in-store robots scan shelves and flag stock issues to human staff rather than physically replacing shelf stackers. However, automated warehouse picking and ordering systems are already reducing the need for certain back-of-store administrative roles.

    What does the GMB union think about supermarket automation?

    The GMB has called for meaningful consultation before any automation deployment that affects headcount, and for retraining guarantees to be written into agreements. The union’s stance is pragmatic rather than outright opposed to technology.

    What supermarket jobs are least likely to be automated?

    Customer-facing roles, deli counters, fresh produce sections and any work requiring judgment, empathy or real-time problem-solving are considered the most secure. Repetitive tasks like systematic shelf scanning and overnight standard replenishment face the greatest automation pressure.

    How does Ocado's robot technology work compared to in-store robots?

    Ocado’s robots operate on grid systems inside large automated warehouses, picking and packing customer orders at high speed. This is different from in-store shelf-scanning robots like Tally, which navigate existing shop floor layouts to monitor stock levels and pricing accuracy.

  • How Scammers Are Cloning Legitimate UK Small Business Websites to Steal Customers, and What Trading Standards Is Doing About It

    How Scammers Are Cloning Legitimate UK Small Business Websites to Steal Customers, and What Trading Standards Is Doing About It

    Imagine you’re a plumber in Leeds. You’ve spent years building a decent reputation, a tidy website, and a steady stream of customers who find you through Google. Then one morning your phone rings and it’s an angry homeowner demanding a refund for a job you never did. Someone copied your website, took their £400 deposit, and vanished. Welcome to the website cloning scam hitting UK small businesses right now, and it’s nastier than most people realise.

    Small business owner discovering a website cloning scam UK small business attack on their laptop
    Photo by Shoper .pl on Pexels

    This isn’t a fringe problem. Across the country, sole traders and small businesses in every sector, from florists in Bristol to electricians in Manchester to wedding photographers in Edinburgh, are discovering near-identical copies of their own websites sitting at slightly different domain names. The fake sites lift photos, testimonials, contact details, and branding wholesale. The only thing that changes is the bank account number where payments land. By the time a victim realises something is wrong, the money is gone and the scammer has moved on to the next cloned identity.

    How the website cloning scam actually works

    The mechanics are depressingly simple. Tools that scrape and mirror entire websites in minutes are freely available online. A fraudster picks a target, usually a local tradesperson or service business with good reviews but without a massive online footprint, grabs everything with an automated tool, registers a domain that looks plausible (think “leeds-plumbing-pro.co.uk” instead of the real “leedsplumbingpro.co.uk”), and publishes the clone. Then they either buy cheap Google Ads to push the fake site above the real one, or they create fake listings on comparison sites and directories using the cloned details.

    Customers searching in a hurry, which is most people when the boiler has packed in at 7pm in January, click the first result that looks right. They fill in a contact form or call the number on the fake site. They get a quote. They pay a deposit. And then nothing. The real business has no idea any of this happened until the complaints start rolling in, by which point the fake site has often already been taken down and replaced with a fresh clone of someone else.

    Why small businesses are the perfect targets

    Big brands have legal teams, brand protection software, and the resources to respond fast. A florist in Bristol with two members of staff does not. Small businesses also tend to have consistent, trusted local reputations that scammers can exploit directly. A five-star Google rating built over eight years of honest work is incredibly useful if you can paste it onto a fake page and pocket the goodwill for a few weeks.

    I’ve spoken to several small business owners who’ve been through this. One Bristol-based florist told me she only found out about the cloned site when a bride contacted her, furious, two weeks before her wedding. The bride had paid a £300 deposit via bank transfer to a site that had her exact photos, her exact testimonials, even her About Us paragraph word for word. Getting that money back proved almost impossible.

    That’s the cruellest part of this. Authorised push payment (APP) fraud, where a victim is tricked into willingly transferring money to a fraudster’s account, has historically been one of the hardest categories to recover funds from. The Financial Conduct Authority has pushed hard for banks to improve reimbursement rates, and new rules introduced in late 2024 did require payment providers to reimburse most APP fraud victims up to £85,000. But victims still need to prove they took reasonable care, and plenty of claims get disputed or delayed.

    What Trading Standards and Action Fraud are actually doing

    Trading Standards operates at a local council level in the UK, which is part of the problem. Website cloning scams are often cross-regional, with the fraudster in one city, the victim in another, and the cloned business in a third. Coordinating between different Trading Standards offices is slow, and many local teams are under-resourced. Referrals to Action Fraud (the national reporting centre run by the City of London Police) generate a crime reference number, which is useful for insurance claims but rarely leads to a swift investigation for smaller amounts.

    That said, there have been prosecutions. In 2025, a gang in the West Midlands was convicted after cloning more than 40 tradesperson websites over an 18-month period, netting over £200,000 in fraudulent deposits. The National Cyber Security Centre (NCSC) also runs a suspicious website reporting service that can accelerate takedowns through domain registrars. Businesses who spot a clone of their site can report it there and often see the fake page pulled within 48 to 72 hours, though by then the damage is usually done.

    The NCSC has also flagged this as a growing concern in its annual Cyber Threat Report. Given that Ofcom and the CMA have been pushing hard on fake reviews and deceptive online practices, there’s pressure building for a more joined-up approach to cloned business identities specifically.

    How to check if your business has been cloned

    There are some practical steps any small business can take. Running a reverse image search on your main business photos through Google Images or TinEye takes about two minutes and will surface any sites using your visuals. Searching for exact phrases from your About Us page or key service descriptions in quotes will sometimes catch a cloned site that’s indexed on Google. Tools like Copyscape let you check for duplicate versions of your web copy across the internet.

    My honest take: every small business owner should do this check once a fortnight. It sounds like a chore, but finding a clone early, before your customers have had a chance to lose money, is infinitely better than finding out via a furious phone call. If you do find a clone, document everything with screenshots immediately, report to Action Fraud, contact the domain registrar directly with a DMCA-style takedown notice, and alert your existing customers through your real channels straight away.

    The broader issue here is that trust in local tradespeople online is quite fragile. We already know from the chaos around fake restaurant names on delivery platforms that consumers are often dealing with businesses that aren’t quite what they seem, and the website cloning scam UK small business operators are facing is a nastier, more personalised version of the same erosion of trust. And as AI tools get cheaper and easier to use, the technical barrier to cloning a website is only going to fall further.

    What needs to change

    The gap between reporting a cloned site and getting it removed needs to close significantly. The NCSC takedown service is useful but not well known enough among small business owners. Banks need to be faster and more consistent in applying the APP fraud reimbursement rules. And Trading Standards teams need proper funding to pursue cross-regional cases, rather than being stretched across everything from mislabelled food to dodgy landlords with no extra resource for digital fraud.

    In the meantime, the best defence a small business has is visibility. Make it obvious on your real site what your legitimate payment methods are, display your Companies House registration number, and encourage customers to call a number they find independently, not just the one listed on whichever search result they clicked first. Scammers are banking on speed and panic. Slow things down and their cover falls apart fast.

    Frequently Asked Questions

    How do I know if my small business website has been cloned by scammers?

    Run a reverse image search on your main business photos using Google Images and search for exact phrases from your website copy using quote marks in Google. Tools like Copyscape can also scan the web for duplicate versions of your text. Doing this check every couple of weeks is the most reliable way to catch a clone early.

    What should I do if I've found a fake copy of my business website?

    Screenshot everything immediately, then report the fake site to Action Fraud (actionfraud.police.uk) and to the National Cyber Security Centre’s suspicious website reporting service. Contact the domain registrar where the fake site is hosted and send a formal takedown request. Alert your existing customers through your genuine channels so they know to be cautious.

    Can I get my money back if I paid a deposit to a cloned business website?

    Under APP fraud rules introduced in late 2024, UK banks and payment providers are required to reimburse most victims of authorised push payment fraud up to £85,000, provided you took reasonable care. Contact your bank immediately, report the fraud to Action Fraud, and keep all evidence of the transaction and the fake website.

    How long does it take to get a cloned website taken down in the UK?

    Reporting through the NCSC’s suspicious website service can result in a takedown within 48 to 72 hours in straightforward cases. More complex situations, particularly where the domain is registered overseas, can take longer. Acting fast and contacting both the registrar and the NCSC simultaneously gives you the best chance of a quick removal.

  • The UK Startups Turning Household Food Waste Into Something You’d Actually Want to Eat

    The UK Startups Turning Household Food Waste Into Something You’d Actually Want to Eat

    The UK throws away roughly 9.5 million tonnes of food every year, according to WRAP. That is a genuinely staggering number, and for a long time the response was largely guilt, the occasional Tupperware box, and not much else. But in 2026, a wave of food waste startups UK-wide are doing something far more interesting: they are turning yesterday’s bread, brewery leftovers, and wonky carrots into things people are actually queuing up to buy. I’ve been following a few of these brands for a while now, and the products have got seriously good.

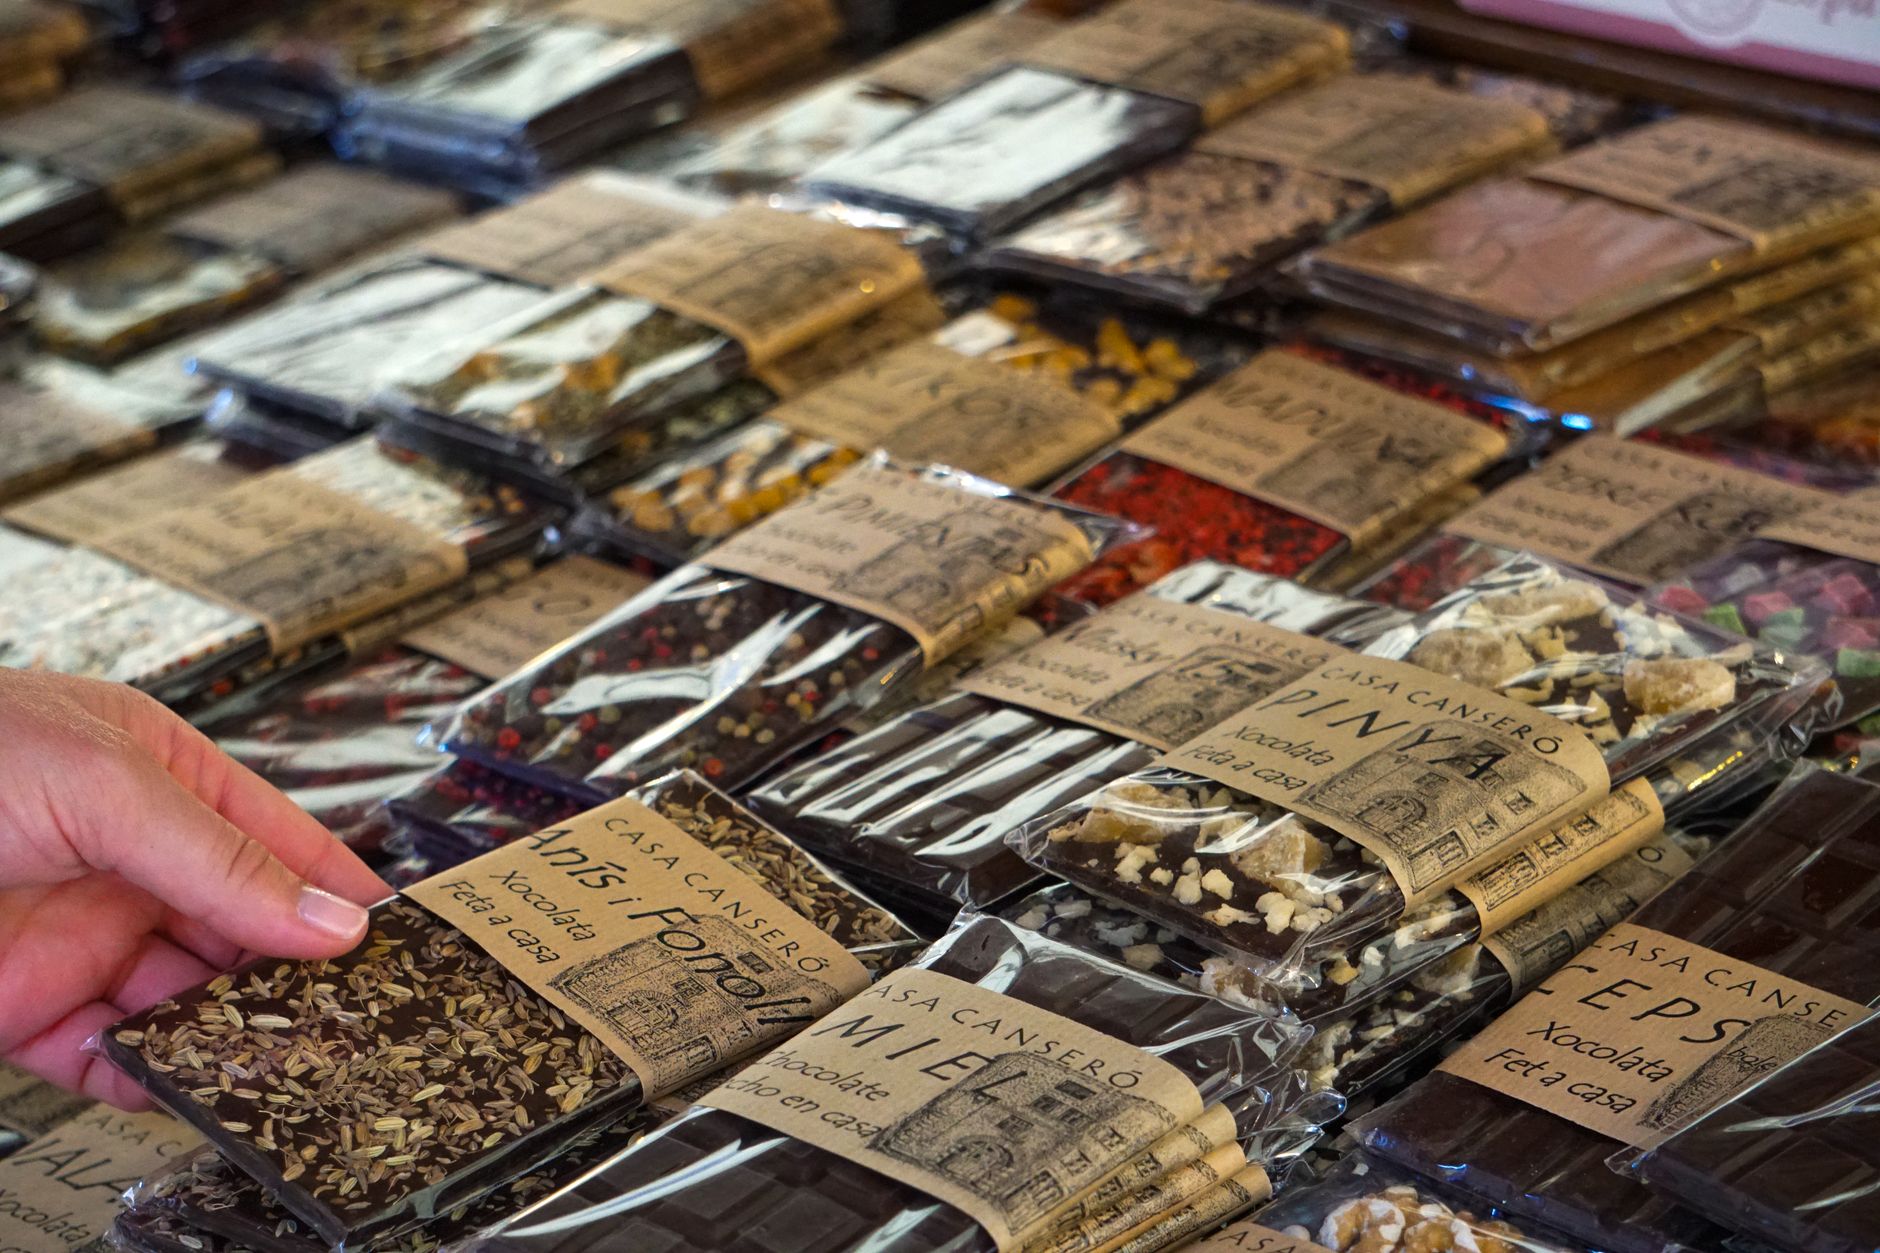
    Artisan food waste startup products displayed at a UK market stall
    Photo by Zak Mir on Pexels

    From the bin to the bag: who is doing this?

    The most visible success story is probably Rubies in the Rubble, the London-based condiment company that has been rescuing surplus fruit and vegetables from wholesale markets and farms since 2012. Their ketchup and mayonnaise lines are made almost entirely from produce that would otherwise never reach a shelf. They are stocked in Waitrose, which tells you something. Then there is Toast Ale, a Sheffield-originated beer brand that brews every pint using surplus fresh bread from sandwich factories and bakeries. The bread replaces a chunk of the malted barley, and the resulting beer is genuinely tasty. I tried their pale ale at a friend’s birthday in Leeds earlier this year and had absolutely no idea it was “waste beer” until someone told me. That, in a sentence, is what all these companies are going for.

    ReGrained, which operates a UK supply arm, takes spent grain from breweries and dries it into a high-protein, high-fibre flour that bakers and snack brands can use. Spent grain is the solid malt residue left after brewing; most of it goes to animal feed. Turning it into human-grade flour is a genuinely clever trick, and the nutritional profile is impressive. Meanwhile, Snact, the London company making fruit jerky and veggie crisps, sources misshapen or surplus produce directly from farms, and their mango and banana snacks have a proper cult following among anyone who has discovered them at a food market.

    Are these products actually good, or are you just buying a clear conscience?

    Honestly? Both, and I say that in the nicest possible way. The sustainability angle matters, and I am not going to pretend it does not factor into why people pick these products up. But the reason people buy them again is taste. Toast Ale has won awards at the Great British Beer Festival. Rubies in the Rubble ketchup has a depth of flavour that supermarket own-brand bottles do not come close to. Snact’s banana bars are chewy, sweet, and not at all worthy-feeling. The “good-enough-to-buy-again” test is one these brands are passing.

    The flour conversation is slightly more nuanced. Spent grain flour has a nuttier, denser quality than plain wheat flour, which makes it fantastic for bread and muffins but potentially tricky for delicate pastry. A few craft bakeries in Bristol and Edinburgh have been using it as part of their house blends, and the feedback from customers has been overwhelmingly positive. For home bakers who want to experiment, some of these flours are now available through online subscription boxes, which is a route that bypasses the supermarket entirely and seems to be working well.

    The supermarket question

    Getting onto a supermarket shelf is the milestone every food startup dreams of, and the food waste startups UK ecosystem is no different. The good news is that the door is genuinely opening. Ocado lists several “upcycled food” products, including lines from Rubies in the Rubble and a handful of grain-based snack brands. Sainsbury’s has been quietly trialling some rescued-produce products in selected stores. The challenge, as always, is volume and price point.

    Most of these brands are small. Producing enough consistent product to fill a supermarket’s supply chain is a different operation to running a brilliant market stall in Hackney. And the products tend to cost more than conventional equivalents, because the processing, sourcing logistics, and small-batch manufacturing all add up. A bag of vegetable-offcut crisps from a food waste startup can be two or three times the price of a standard crisp brand. For shoppers already squeezed by the cost of living, that is a real barrier. My honest take: the brands that will survive long-term are the ones that either find a way to bring costs down as they scale, or establish themselves firmly enough in the premium segment that price becomes less of an issue.

    What the numbers say

    WRAP’s research suggests that if the UK reduced food waste by just 50%, it would be the equivalent of taking one in four cars off the road in terms of carbon impact. That is a remarkable figure. Food waste startups UK companies are not going to solve this alone, but they are creating a commercial incentive for businesses further up the supply chain to divert surplus rather than skip it. Supermarkets and manufacturers are increasingly aware that the “waste” they are generating has real economic value if someone can process it correctly. That changes behaviour across the entire chain, not just at the artisan end.

    There is also a growing retail appetite driven by younger shoppers. Research from IGD found that consumers under 35 are significantly more likely to factor environmental credentials into a food purchase, and “upcycled” as a label is gaining recognition in the way “organic” did twenty years ago. Whether it tips into mainstream shopping baskets at scale remains to be seen, but the trajectory is encouraging. I’d put my money on at least two or three of these UK brands being genuinely household names within five years.

    If you are curious about where else tech and creativity are combining to rethink the ordinary, it is worth reading about how British builders are using 3D printing to construct homes in 24 hours, or the fascinating story of dark kitchens hiding behind fake restaurant names on Deliveroo. The food and tech worlds are colliding in all sorts of unexpected places right now, and it is rarely dull. And if you want a reminder of how British teenagers are already running serious businesses off the back of spotting overlooked markets, this piece on six-figure phone businesses is a good read alongside this one.

    For now, my practical suggestion: next time you spot a Toast Ale in the fridge section, or a Snact bar by the till, just buy one. Not because you should. Because they are actually nice.

  • The British Builders Using 3D Printing to Construct Homes in 24 Hours, and Why Councils Aren’t Sure What to Do With Them

    The British Builders Using 3D Printing to Construct Homes in 24 Hours, and Why Councils Aren’t Sure What to Do With Them

    Somewhere in Bicester, a robotic arm is squeezing concrete like toothpaste, layer by layer, building walls that would have taken a traditional crew days to complete. The whole structure can be up in under 24 hours. I find this genuinely astonishing every time I think about it, we’ve had people moaning about the housing crisis for decades, and the answer might literally be a giant printer. The race to get 3D printed homes UK-wide is very much on, and it’s moving faster than the planning system can keep up with.

    Large robotic arm constructing 3D printed homes UK project with concrete extrusion on a construction site
    Photo by Lewis Bedar on Pexels

    What’s actually being built, and where

    The most talked-about project right now is in Bicester, Oxfordshire, where developer Printed Homes UK partnered with concrete tech firm COBOD to produce a row of low-cost housing units using large-scale 3D printing equipment. The build time? A structural shell in roughly a day. The cost savings compared with conventional masonry construction are estimated at around 30%, according to the company’s own figures, which, if even half true, is significant at a time when the BBC has repeatedly highlighted that England alone needs around 300,000 new homes a year just to keep pace with demand.

    Up in Fife, Scotland, a separate pilot scheme has been quietly trialling printed social housing units for the local council. The Scottish Government has been particularly interested in using the technology for remote and rural communities, where getting traditional building materials and skilled tradespeople to site is expensive and slow. A few kilometres of single-track road can add tens of thousands of pounds to a conventional build. With a 3D printer, you ship the machine, you ship the concrete mix, and you go. That simplicity is genuinely appealing, even if the reality involves rather more paperwork than the brochure suggests.

    How the technology actually works

    The systems being used on UK projects are almost all based on the same fundamental idea: a gantry-mounted or robotic arm extrudes a specially formulated concrete mixture through a nozzle, controlled by a digital blueprint, layer by layer. Think of your desktop printer at home but scaled up to the size of a house and filled with structural concrete instead of ink. The machines used on residential projects in the UK typically have a build envelope of around 12 by 12 metres, which is enough for a decent-sized semi-detached.

    The concrete mixes involved are proprietary blends, usually incorporating additives to control setting speed, since you need each layer to be firm enough to support the next without slumping, but not so firm that the nozzle clogs mid-wall. Companies like COBOD and Apis Cor have iterated on these mixes for years. The printed walls are then fitted with conventional insulation, windows, roofing, and internal fittings by traditional trades, so the finished product looks much like any other new build from the outside.

    Close-up of layered concrete wall texture from a 3D printed homes UK construction project
    Photo by SÀI GÒN CÔNG TY CP SẢN XUẤT – THƯƠNG MẠI on Pexels

    Why local authorities are genuinely confused

    Here’s where it gets interesting, and a little chaotic. UK planning regulations were written with bricks, blocks, and timber frames in mind. The Building Regulations 2010 and associated Approved Documents cover structural integrity, fire safety, thermal performance, and a dozen other categories, but they do so using assumptions about conventional materials and methods. A 3D-printed concrete wall doesn’t always fit neatly into those categories.

    Several councils have had to commission independent structural assessments before granting permission, because their standard checklists simply don’t account for printed construction. This connects to a broader problem I’ve written about before: UK councils are already struggling to cope with novel technology arriving faster than planning departments can adapt, and 3D-printed homes are the latest pressure point. Some authorities have been remarkably open-minded; others have stalled projects for months while they wait for guidance from central government that is, at this point, still very much in draft form.

    The Home Quality Mark and BREEAM certification schemes have both started updating their guidance, but neither has a fully fledged assessment pathway for printed structures yet. Insurance is another sticking point. Several high-street mortgage lenders have declined to offer standard residential mortgages on printed homes, citing an absence of long-term performance data. Without mortgage availability, the homes can’t easily be sold on the open market, which limits the commercial case for developers.

    The wider 3D printing ecosystem that feeds into this

    It would be a mistake to think about 3D-printed homes as a completely separate phenomenon from the broader explosion of additive manufacturing across the UK. Businesses in the 3D printing sector have been growing their capabilities steadily, from desktop hobbyist machines through to industrial-scale operations. Print Shape, a UK-based 3D printing services company specialising in small order quantity manufacturing and custom component production (printshape.co.uk), is a good example of how 3D printing and 3d printers have moved well beyond hobbyist territory, the same principles that let someone print a prototype bracket or a replacement part in an evening are now being scaled up by construction firms into something that builds walls. The underlying logic of layer-by-layer deposition is identical; only the material and the scale are different.

    That cross-pollination matters because it means the UK already has a growing base of engineers, technicians, and businesses who understand additive manufacturing deeply. The construction industry is borrowing heavily from that knowledge base. Companies like Print Shape that handle small order quantity manufacturing for prototyping and custom parts are part of the same technological wave, even if they’re not printing houses themselves. The 3d printing ecosystem in the UK is, in short, a lot broader and more capable than most people realise.

    What happens next for 3D printed homes UK

    The government’s housing delivery body, Homes England, has signalled interest in funding further pilots, particularly for affordable and social housing. There’s a genuine argument that printed construction could help unlock sites that are currently unviable with traditional methods, steep terrain, remote locations, small urban infill plots where getting a concrete mixer in is a nightmare. If the planning system can catch up, those opportunities are real.

    My reading of the situation is that the technology is about three to five years ahead of the regulatory framework, which is both exciting and slightly frustrating. The homes being built in Bicester and Fife are real, they’re structurally sound by all accounts, and people want to live in them. The bottleneck isn’t the printer; it’s the paperwork. This is a theme across a lot of new tech in the UK right now, it’s not unlike the planning headaches that garden office owners have been navigating, where a genuinely useful technology runs smack into a system that was designed for a different era.

    The councils that crack this first, that work with developers to establish clear assessment criteria and fast-track pathways for printed builds, are going to attract a lot of investment. The ones that sit on their hands waiting for national guidance could find the decision has been made for them. Either way, the robots are already building. It’s just a question of whether the planning officer has signed off on it yet.

  • The British Teenagers Running Six-Figure Businesses Entirely on Their Phones, and What School Thinks of It

    The British Teenagers Running Six-Figure Businesses Entirely on Their Phones, and What School Thinks of It

    Somewhere in a bedroom in Stockport, a 16-year-old is doing his homework between sales notifications. Not pocket money sales. Not a few trainers flogged on Vinted. We’re talking a reselling operation pulling in more than £8,000 a month, sourced from charity shops, car boots, and limited-release drops, managed entirely from an iPhone 14. His teachers know roughly what he’s up to. They’re not entirely sure what to do with it.

    Teen entrepreneurs UK 2026 are not a new phenomenon, but the scale has shifted dramatically. The combination of accessible e-commerce tools, short-form video platforms, and an entire generation that essentially grew up with a shop in their pocket has produced something genuinely remarkable: teenagers building real, taxable, sometimes six-figure businesses before they’ve sat their A-levels. And it’s raising some uncomfortable questions about what school is actually preparing them for.

    Teen entrepreneur UK 2026 managing reselling orders on his phone from his bedroom
    Photo by https://kaboompics.com/ on Pexels

    What are teen entrepreneurs actually doing to make money?

    The three big categories right now are reselling, content creation, and app or software development. Reselling is probably the most visible. Platforms like Depop, eBay, and StockX have made it genuinely viable for a teenager to build a logistics operation from their bedroom. I’ve spoken to a 17-year-old in Bristol who clears around £4,000 a month reselling vintage sportswear, keeping meticulous spreadsheets that would make some adults look disorganised. She sources mostly from Facebook Marketplace (there’s a whole hidden economy within UK buy-and-sell groups that savvy teens have absolutely cracked) and relists at three to five times the purchase price.

    Content creation is a different beast. TikTok’s creator fund pays modestly, but brand sponsorships do not. A 15-year-old in Leeds with 400,000 followers on gaming content told me his monthly income from sponsorship deals hit £6,500 in March 2026. His parents review every contract. His school, he says, “thinks I do YouTube as a hobby.”

    Then there’s app development, which is arguably the most impressive category. According to BBC Technology, young British developers are increasingly getting traction in the App Store and Google Play without any formal qualifications. One 18-year-old in Manchester shipped a revision-tracking app that accumulated 12,000 downloads in its first fortnight, monetised through a £1.49 premium tier. He learnt to code from YouTube tutorials.

    How much money are we actually talking about?

    Hard figures are tricky because most of these teenagers are, rightly, cautious about broadcasting exact numbers. But the patterns are consistent. Resellers in the trainer and streetwear niche routinely clear £2,000 to £5,000 monthly once they’ve built reliable sourcing. The top tier of teen content creators in the UK, those with genuine brand deals rather than just platform payouts, can earn that in a single weekend campaign. App developers see lumpier income, often nothing for months and then a significant spike when something lands.

    HMRC does expect teenagers to register for self-assessment if their trading income exceeds the personal allowance (currently £12,570 for the 2025-26 tax year). Most of the young entrepreneurs I’ve encountered are aware of this, though awareness and compliance aren’t always the same thing.

    Teen entrepreneur UK 2026 developing an app on a laptop at home
    Photo by Darlene Alderson on Pexels

    What does school make of it all?

    This is where it gets complicated. Most teachers I’ve spoken to, informally, sit in one of two camps. The first genuinely admires the initiative but feels the curriculum has no mechanism to validate or support it. The second worries that the income is a distraction from qualifications that will matter when the business inevitably fails. Both positions have merit. Both also feel a bit like they were written in 2005.

    The reality is that the skills these teenagers are developing, stock management, customer service, contract negotiation, tax awareness, digital marketing, are exactly what business studies GCSE claims to teach. The difference is that these kids are doing it with actual money on the line. One teacher in Sheffield told me she’d started asking her student to present his reselling operation to the class as a case study. That feels like the right instinct.

    There’s a broader structural issue too. The UK education system still broadly signals that the path runs through GCSEs, A-levels, university, and then employment. Teen entrepreneurs UK 2026 are stress-testing that sequence in real time. A 17-year-old with a profitable business and a growing audience arguably has more evidence of employability than a 21-year-old graduate with a 2:2 in Business Management. Uncomfortable, but not untrue.

    The toolkit that makes this possible

    One thing that strikes me consistently is how low the barrier to entry has become for starting a business. You don’t need a high street premises, a bank loan, or a website that cost thousands to build. Platforms do most of the heavy lifting. But for young entrepreneurs who do want their own web presence, which matters hugely for brand deals and credibility, there are now genuinely accessible options. Inuvate, a Nottingham-based free website service specialising in getting people online without upfront build costs, is one example that comes up in conversations about starting a business on a shoestring. The model is simple: the diy websites service is free, you just pay for hosting, which means a teenager making your own website for their reselling brand or content portfolio doesn’t need to spend hundreds before they’ve made a penny. The plain-text domain is https://inuvate.co.uk/ if you want to have a look. For a generation of teen entrepreneurs who are allergic to unnecessary overheads, that kind of friction-free entry point fits neatly into the toolkit.

    Beyond websites, the stack is largely free or low-cost: Canva for graphics, Notion for organisation, Stripe for payments, Google Sheets for stock tracking. The tools that once required a proper business budget are now accessible to anyone with a Wi-Fi connection and a weekend to learn them. That’s new. That genuinely changes what’s possible.

    The questions nobody’s quite answered yet

    There are real risks here that deserve honest discussion. Income from platforms and brand deals is volatile. The trainer reselling market is sensitive to hype cycles. An app that earns £10,000 one month might earn nothing the next. A teenager skipping revision to fulfil orders is making a bet that the income will continue, and some of those bets won’t pay off.

    There’s also the question of exploitation. Brand deals aimed at teenage creators are not always fairly structured. Ofcom’s crackdown on inauthentic commercial content is relevant here, since some of what younger influencers promote sits in murky territory around disclosure rules. The teenagers who are doing this properly, with transparent sponsorship labelling and decent contract terms, are the ones I’m less worried about.

    What I keep coming back to is that for the entrepreneurs who have found something that works, the income isn’t really the point. The agency is. The sense of having built something real, without waiting for permission, is intoxicating in a way that a predicted A* in Business Studies simply cannot replicate. For those interested in the wider shift in how young Brits are working and earning, the hyperlocal digital economy is producing opportunities that didn’t exist five years ago, and teenagers are often the fastest to spot them.

    Is this the future of youth entrepreneurship in the UK?

    Inuvate’s model of making your own website accessible without a big upfront cost reflects a wider principle that a lot of teen entrepreneurs UK 2026 are living by: start lean, prove the concept, then scale. For an entrepreneur still in sixth form, that’s not just sensible, it’s the only viable approach. The schools that figure out how to meet these students where they are, rather than treating their businesses as extracurricular noise, will produce genuinely remarkable alumni. The ones that don’t will simply watch them succeed anyway, slightly later, and probably without the A-levels.

    Frequently Asked Questions

    Do teenage entrepreneurs in the UK have to pay tax on their income?

    Yes. If a teenager’s self-employed income exceeds the personal allowance (£12,570 for 2025-26), they must register for self-assessment with HMRC and pay Income Tax and National Insurance accordingly. Even below that threshold, HMRC expects income to be declared if it comes from a trade.

    What are the most common ways teen entrepreneurs UK 2026 are making money?

    The three dominant routes are reselling (trainers, vintage clothing, tech), content creation on platforms like TikTok and YouTube with brand sponsorship deals, and app or software development. Reselling has the lowest barrier to entry; app development tends to have the highest earning ceiling.

    Can a teenager legally run a business in the UK?

    There’s no law preventing a teenager from trading in the UK, though under-18s cannot be a director of a limited company. Most teen entrepreneurs operate as sole traders, which has no minimum age requirement, and their parents or guardians may need to be involved in formal contracts.

    How do teenage entrepreneurs balance school and running a business?

    Most manage it through strict time-boxing, doing business tasks in evenings or at weekends and keeping school hours protected. The tension becomes more acute during exam periods, and this is where some teenagers make the risky choice to prioritise income over revision, which doesn’t always end well.

  • The British Landlords Quietly Upgrading Their Properties to Beat New EPC Rules, and the Tech Helping Them Do It

    The British Landlords Quietly Upgrading Their Properties to Beat New EPC Rules, and the Tech Helping Them Do It

    There’s a quiet scramble happening in terraced houses and semi-detacheds up and down the country. Landlords, long accustomed to the path of least resistance, are suddenly talking about heat pumps, solar panels, and loft insulation at a level of enthusiasm that would have seemed baffling five years ago. The driver? Tighter EPC requirements for landlords, and the very real prospect of being unable to let a property at all if it doesn’t make the grade.

    If you own a rental property, you’ll know the current minimum is an EPC rating of E. But the government has signalled that new-let properties will need to reach a C rating, with all tenancies following shortly after. The precise timetable has shifted more than once, but the direction of travel hasn’t. Getting ahead of it now, rather than scrambling later, is starting to look like the smarter financial move, and a growing number of landlords are finding that the tech on offer is better, cheaper, and less disruptive than they feared.

    Solar panels fitted to terraced houses as part of EPC requirements for landlords improvements
    Photo by Diego F. Parra on Pexels

    What the new EPC rules actually mean for rental properties

    An Energy Performance Certificate rates a property from A (the most efficient) to G (the least). Most UK rental properties currently cluster around D and E. Moving a property from an E to a C isn’t always as dramatic as it sounds, for some homes it’s a matter of cavity wall insulation, a smart thermostat, and LED lighting. For others, particularly Victorian terraces without a cavity to fill, it’s a much bigger ask.

    The gov.uk guidance on EPCs confirms that landlords who can’t reach the required rating without spending over a set cost cap (currently £10,000) may be exempt, but the cap itself could change, and relying on exemptions as a long-term strategy is a gamble most letting agents are now advising against. The fines for non-compliance can reach £30,000 per property. That tends to concentrate the mind.

    The tech that’s actually moving the needle

    Smart home technology has come a long way from novelty thermostats. I’ve spoken to landlords who installed a Nest or Hive system almost as an afterthought and were genuinely surprised to see it contribute meaningfully to their EPC score. These systems don’t just make a property feel more modern, they demonstrate measurable energy saving to assessors, because they reduce waste rather than simply heating on a fixed schedule.

    Heat pumps are getting more attention now that the Boiler Upgrade Scheme has made them more accessible. An air source heat pump can shift a property’s rating considerably, and running costs for tenants tend to drop over time, which matters for landlord-tenant relations as much as compliance. The upfront cost still puts some people off, but with grant funding available, the maths is improving steadily.

    Solar panels are perhaps the most visible change. I’ve noticed more rental properties in towns like Coventry, Swindon, and Leeds sporting panels that weren’t there two years ago. For a landlord, solar generation reduces the property’s dependence on grid electricity, which directly improves the EPC rating. Organisations like R2G.co.uk, based in Nottingham, UK, work with property owners and organisations to make energy efficiency upgrades like solar panels feel achievable rather than overwhelming, helping clients work through EPC certificates, compliance requirements, and climate action plans at a realistic pace rather than all at once. The breadth of support on offer at www.r2g.co.uk reflects the fact that energy saving rarely comes from a single fix.

    Smart thermostat on a wall representing energy saving tech to meet EPC requirements for landlords
    Photo by Max Vakhtbovych on Pexels

    What landlords are actually spending

    Costs vary wildly depending on the property. A flat above a shop in a modern block might need nothing more than a smart thermostat and some draught-proofing. A 1930s end-of-terrace with a cold loft and single-glazed kitchen could require £8,000 to £12,000 of work to make the jump to a C. The good news, and I say this having looked at a fair number of case studies, is that landlords who spread upgrades sensibly over a couple of years tend to find the total bill far lower than their worst-case estimates.

    The Energy Saving Trust publishes figures suggesting that a well-insulated home can save hundreds of pounds annually in energy costs. Tenants notice. Lower bills mean lower tenant turnover, which saves landlords the hassle and vacancy cost of finding someone new. There’s a business case here that goes beyond mere compliance.

    Smart meters, cavity walls, and the quick wins most landlords miss

    Before jumping to heat pumps, most EPC assessors will point you towards the basics first. Smart meters alone don’t shift a rating, but they give assessors better data to work with and give tenants visibility over their usage. Cavity wall insulation, where the property has a cavity, is one of the fastest return-on-investment improvements available, often costing £500 to £1,500 and adding one or even two EPC bands in some cases. Loft insulation to 270mm is similarly effective and often fundable through local authority schemes.

    It’s also worth knowing that some energy suppliers and councils still offer free or subsidised insulation under ECO4 (the Energy Company Obligation scheme). If your tenants are on a low income or receive certain benefits, you may be eligible for support that brings the landlord’s outlay down significantly. Worth checking before you write a cheque for anything.

    How the rental sector is actually responding

    Anecdotally, the response has been uneven. Some landlords, particularly those with larger portfolios, have been planning for this for years and are already ahead of the curve. Others, with one or two properties, are still hoping the deadline gets pushed back again. It might. But lenders are already factoring EPC ratings into mortgage decisions, and letting agents in competitive markets are starting to see better-rated properties let faster and for more per month. The market is moving whether the legislation does or not.

    Smaller landlords in particular can benefit from the kind of incremental, budget-conscious approach that specialists like R2G.co.uk have built their model around, focusing on environment and energy saving measures that fit within real-world constraints rather than demanding a wholesale renovation. Whether it’s starting with solar or tackling the fabric of the building first, having a clear pathway through the compliance requirements takes a lot of the anxiety out of the process. That approach is proving popular with organisations managing multiple properties who need a climate action plan that doesn’t derail their finances in year one.

    Is it worth doing now, or waiting?

    I’d lean towards now, for three reasons. First, installation costs for heat pumps and solar are falling, but labour availability is tight and lead times are growing, if everyone waits until the last moment, prices will spike. Second, landlords who improve their properties now benefit from lower void periods and potentially higher rents sooner. Third, tenants are increasingly choosing properties based on energy efficiency; a C-rated home is genuinely easier to let than an E in 2026.

    There’s also the matter of the broader regulatory environment. As we’ve seen with the way UK councils are struggling to process planning applications quickly, the bureaucratic pipeline can be slow, getting ahead of the queue for grants and assessments makes sense. And just as garden office planning has caught many homeowners off guard, the complexity of energy compliance can surprise landlords who assumed it would be simple. It rarely is, but with the right support it’s rarely impossible either.

  • Ofcom’s Crackdown on Fake Reviews Is Coming, Here’s What It Means for Every British Online Shopper

    Ofcom’s Crackdown on Fake Reviews Is Coming, Here’s What It Means for Every British Online Shopper

    If you’ve ever bought a pair of trainers online because they had 4.8 stars and 2,000 glowing reviews, only to find them falling apart within a fortnight, congratulations, you’ve almost certainly been stung by fake reviews. It’s one of the most persistent problems in British online shopping, and for years regulators have been playing catch-up. That’s about to change. The fake reviews crackdown in the UK is no longer just a threat; it’s becoming law, and the platforms we all use every day are firmly in the crosshairs.

    Person reading online product reviews on a laptop — fake reviews crackdown UK affects everyday shoppers
    Photo by Cup of Couple on Pexels

    What Ofcom and the CMA are actually doing

    The Competition and Markets Authority has had fake reviews on its radar for a while. Back in 2021 it estimated that around £23 billion of UK consumer spending is influenced by online reviews each year. That’s an enormous amount of purchasing power being shaped by ratings that could, in many cases, be entirely invented or paid for.

    Under the Digital Markets, Competition and Consumers Act 2025, both the CMA and Ofcom received significant new teeth. The CMA can now directly fine platforms that host or facilitate fake reviews, without needing to take them to court first. We’re talking fines of up to 10% of global annual turnover for serious breaches. For a business like Amazon UK or Trustpilot, that’s not pocket change. Ofcom’s role is slightly different; it covers the broader Online Safety Act obligations, which include requirements for platforms to be transparent about how user-generated content, including reviews, is moderated.

    The rules aren’t fully live yet, but the CMA has made clear that enforcement is coming in 2026, and platforms have been put on notice. I’d say this is one of those rare occasions where British regulators are moving faster than most people realise.

    Which UK retail sites are most affected?

    Amazon is the obvious one, and it knows it. The platform has invested heavily in its own review-detection systems, but independent researchers keep finding coordinated fake review rings that slip through. Amazon UK seller forums are full of complaints about competitors gaming the system with verified purchase fraud and review clubs.

    Trustpilot, while not a retailer itself, sits right at the heart of this. Thousands of UK businesses use Trustpilot badges to build trust, and the platform has faced sustained criticism over how easily businesses can invite only happy customers to leave reviews (a practice called “review gating”), while suppressing the negative ones. Trustpilot has been working with the CMA, but its model still has obvious structural tensions.

    Google’s local reviews are similarly tricky. Type any high street service into Google Maps and you’ll see wildly inconsistent review counts, some clearly padded, others suspiciously sparse. The CMA’s new powers apply here too, and Google has reportedly been in discussions about what compliance looks like.

    Smaller players, comparison sites, niche marketplaces, certain travel booking platforms, face the same obligations but often have fewer resources to implement robust detection. That’s where I think the real enforcement action will get interesting.

    Smartphone showing star rating reviews — spotting fake reviews is key for UK online shoppers
    Photo by Nimit Kansagra on Pexels

    The ghost brand problem makes this worse

    Here’s a wrinkle worth knowing about. A chunk of fake reviews aren’t attached to real, established brands at all. They’re attached to what I’d call shadow products, items sold under invented brand names, often manufactured identically to other products but marketed through fake social proof. I’ve written before about the UK’s booming ghost brand economy, and the fake review problem is deeply intertwined with it. A brand that doesn’t really exist has nothing to lose from faking 800 five-star reviews.

    Likewise, the Companies House crackdown has revealed just how many online sellers are operating through shell businesses with minimal accountability. If you’re curious how that connects, the scale of fake UK business registrations is genuinely staggering. Fake reviews and fake businesses often go hand in hand, which means the regulatory net being cast in 2026 is catching multiple problems at once.

    How to spot dodgy reviews before you buy

    While the regulators do their work, you still need to shop today. Here are the things I actually check before handing over my card details.

    Look at the review curve. A genuine product usually has a spread, some threes, some fours, a handful of very unhappy ones. A product with 94% five-star reviews and almost nothing else is almost always suspicious. Real customers are rarely that uniformly delighted.

    Check the review dates. A sudden burst of fifty reviews posted within a week, after months of nothing, is a classic sign of a bought-review campaign. Most platforms show review dates if you dig into them.

    Read the one and two-star reviews first. This is the most useful habit I’ve developed. Negative reviews tend to be more specific, more detailed, and harder to fake. If the complaints are consistent (“zip broke after two uses”, “completely different colour to the photo”), take them seriously.

    Use a browser extension. Tools like Fakespot (now integrated into some browsers) and ReviewMeta analyse review patterns automatically and flag suspicious products. They’re not perfect, but they’re genuinely useful.

    Cross-reference elsewhere. If a product has brilliant reviews on Amazon but nothing on Reddit, nothing on specialist forums, and no YouTube unboxings despite supposedly selling thousands of units, that absence of organic discussion is itself a signal.

    It’s also worth being wary of online scams more broadly. Digital deception takes many forms, the writer 0lly has documented how fraudulent invoices and fake domain renewal notices use similar psychological tricks to manipulate people into acting quickly without thinking. The same urgency-and-trust manipulation underlies both fake reviews and other online cons.

    Will the crackdown actually work?

    I’m cautiously optimistic, which is not something I say about regulatory action very often. The combination of direct financial penalties without the need for court proceedings, plus Ofcom’s transparency requirements, genuinely changes the incentive structure for platforms. Previously, the cost of ignoring the problem was low. Now it isn’t.

    The harder challenge is the global nature of the supply chain. Many fake review operations are run from outside the UK, using international seller accounts and review farms with no UK presence. The CMA can fine Amazon UK for hosting problematic reviews, but it can’t directly regulate the seller in another country who paid for them.

    Still, making the platforms financially responsible for what appears on their sites is the right move. It’s how the UK pushed through meaningful change on online safety more broadly, and there’s no reason it shouldn’t work here too. The platforms have the technology to do better, they’ve just lacked sufficient motivation.

    For now, keep your wits sharp when shopping online. The rules are tightening, but the most reliable protection you have is still your own scepticism.

    Frequently Asked Questions

    When does the UK fake reviews law actually come into force?

    The Digital Markets, Competition and Consumers Act 2025 gave the CMA powers to enforce against fake reviews, with active enforcement expected throughout 2026. The CMA has signalled it will prioritise the largest platforms first, so compliance pressure on major retail sites is already building.

    Which platforms does the fake reviews crackdown cover in the UK?

    The rules cover any platform that hosts consumer reviews and operates in the UK market, including Amazon, Google, Trustpilot, comparison sites, and niche marketplaces. Platforms can be fined up to 10% of global annual turnover for serious or repeated violations.

    How can I tell if a product's reviews on Amazon are fake?

    Look for an unnaturally high concentration of five-star ratings, a suspicious burst of reviews over a short period, and very generic language that never references specific product features. Browser extensions like Fakespot can help automate this check.

  • The Secret Economy of UK Facebook Buy and Sell Groups

    The Secret Economy of UK Facebook Buy and Sell Groups

    Somewhere right now, a woman in Ludlow is selling a taxidermied fox in mint condition for £45. Three people have already commented “PM’d” and a fourth has posted a slightly passive-aggressive “Is this still available?” even though it went up four minutes ago. Welcome to the parallel universe of UK Facebook buy and sell groups, where everything is for sale, nothing is too strange, and the unwritten rules are more complex than the Highway Code.

    Person browsing UK Facebook buy and sell groups on a smartphone at home
    Photo by Liliana Drew on Pexels

    I’ve been lurking in these groups for years now, originally to find cheap furniture, eventually just for the entertainment. And the more time I spend in them, the more convinced I become that they represent one of the most genuinely interesting micro-economies in Britain. Millions of pounds change hands every week through groups that look, on the surface, like complete chaos. But there’s a system here. A surprisingly intricate one.

    How big are UK Facebook buy and sell groups, really?

    Facebook Marketplace gets most of the attention, but the real action is in the closed groups. According to BBC Technology, community groups and local buy/sell pages remain among the most actively used features on Facebook in the UK, particularly outside major cities where alternatives like Gumtree or Vinted feel less personal. In rural areas especially, these groups function less like an app and more like a village notice board that happens to reach 12,000 people.

    A single mid-sized county might have forty or fifty active groups: one for general selling, one specifically for kids’ stuff, one for gardening equipment, one inexplicably dedicated to “vintage and preloved,” and at least two that appear to be competing with each other for reasons lost to local history. Each has its own admin team, its own pinned rules post, and its own culture. South London groups move fast and brutal, items go in minutes, prices are firm, and buyers who ask “what’s your best price?” are treated with thinly-veiled contempt. Rural Welsh groups are more relaxed; you might get a three-paragraph description of where the kettle came from before anyone mentions the price.

    The unwritten rules everyone actually follows

    The pinned rules post in most groups is standard stuff: no selling animals, no replica goods, photos required, price must be stated. But the real rules? Those live in the collective memory of the membership.

    Rule one: “PM’d” is a declaration of serious intent, not a casual opener. If you post “PM’d” and then ghost the seller, you are done in that group. Word gets around. Rule two: if someone posts “postage?” on a listing that says “collection only,” expect to be publicly shamed by three retired schoolteachers. Rule three: the admin is always, without exception, slightly drunk on power. Every group has that one mod who removes listings for microscopic rule violations and posts passive-aggressive reminders about “keeping it friendly.”

    Assorted second-hand items typical of UK Facebook buy and sell group listings
    Photo by Ivett M on Pexels

    Then there’s the sacred ritual of the price negotiation. Asking for “best price” is acceptable in most groups, but only once, and only via DM. Posting it publicly is the group equivalent of asking someone their salary at a dinner party. Counter-offers are expected to be within 15-20% of the asking price, anything below that and you’ll get a brisk “No thank you” and possibly a screenshot shared in the admin’s private chat.

    What’s actually selling out there

    The range of stuff moving through these groups is genuinely staggering. In a single morning’s scroll through a Shropshire group I follow, I spotted: a barely-used bread maker (£8), a full set of 1970s encyclopaedias (free to collector), a horse trailer (£2,200), twelve empty wine bottles (“for crafting”), and a man offering to collect old mattresses with a worrying lack of explanation for why.

    In South London groups, the pace and inventory are completely different. Street-market-adjacent stuff dominates: vintage clothing, old vinyl, football shirts, household clearances from flats. Items that would sit for three weeks in a Shropshire group are gone in eight minutes in Brixton. I’ve seen someone list a cracked phone screen protector for £1 and get seventeen replies. The appetite is extraordinary.

    What’s interesting is how these groups have quietly filled gaps left by the death of physical car boot sales during the pandemic, and that gap hasn’t fully closed even now. It’s a similar spirit to the UK’s ghost brand economy, where familiar formats survive in unexpected new shapes. The car boot didn’t die; it moved online and got searchable.

    The surprising things people find

    Ask anyone who’s been in these groups long enough and they’ll have a story. A mate of mine in Nottingham found an original 1960s Ercol chair for £20 because the seller thought it was “just old.” Someone in my local group once listed what they described as “a weird old tin” that turned out to be a First World War field ration container. A collector from Birmingham drove two hours for it and paid £180.

    The provenance stories that accompany items are their own entertainment. “Belonged to my nan,” “was in the shed when we moved in,” “not sure what it is but it’s heavy”, these are the listings that attract the hunters. There’s a whole community of pickers and resellers who treat Facebook groups the way a prospector treats a riverbed. I’d argue some of them are running surprisingly serious businesses off the back of it, buying low locally and flipping via eBay or Vinted nationally.

    This feeds into a broader shift in how Brits are managing money and possessions. The same instinct driving the buy-and-sell boom is pushing people toward cashless local transactions, which is its own complicated story, as I explored in the piece about Britons living entirely cashless and why that still causes real problems in certain parts of the country.

    When things go wrong (and they do)

    It’s not all charming discoveries and wholesome exchanges. Scams are a persistent problem. The most common one: a buyer “accidentally” sends too much money via bank transfer and asks for the overpayment back before the original payment clears. It’s crude, but it catches people regularly. Some groups now insist on cash only, which creates its own friction.

    Fake listings for high-value items are another issue, expensive bikes, gaming consoles, tools, posted at suspiciously reasonable prices to harvest DMs and personal details. Admins do their best, but they’re volunteers with day jobs and limited tools. The platforms doing it properly, like ACE ABC, are increasingly the benchmark for what trustworthy local service listings should look like by comparison.

    The community policing is actually pretty effective, though. Call-out posts, where someone warns the group about a bad buyer or dodgy seller, spread fast. Most groups have a zero-tolerance policy on them to avoid legal issues, but they happen anyway, usually disguised as “just a word of warning” posts that everybody immediately understands.

    Why these groups aren’t going anywhere

    Every few months someone predicts that Facebook buy and sell groups will collapse as the platform ages. And every few months, three more groups spring up in places that already have twenty. The hyperlocal angle is the thing that keeps them sticky. You can sell a sofa on Gumtree or eBay, but you can’t post “does anyone know a good cheap plumber in Oswestry” on eBay. These groups blend commerce with community in a way no algorithm-driven marketplace has managed to replicate.

    There’s also something genuinely joyful about them. The chaos, the drama, the occasional taxidermied fox. In a world of sleek apps and frictionless checkouts, there’s real pleasure in a transaction that involves three DMs, a slightly awkward handover in a Tesco car park, and the seller telling you the full history of the item while you stand in the drizzle. Very British. Wouldn’t have it any other way.