Category: News

  • Why Thousands of Brits Are Turning Their Lofts Into Micro Data Centres, and the Risks They’re Not Telling Their Insurers

    Why Thousands of Brits Are Turning Their Lofts Into Micro Data Centres, and the Risks They’re Not Telling Their Insurers

    Somewhere in Britain right now, someone is lugging a rack-mounted server up a loft hatch. Maybe it is running a cryptocurrency node. Maybe it is storing every photo and video their family has ever taken. Maybe it is crunching AI workloads overnight. The home server setup UK scene has exploded quietly over the past couple of years, and the people doing it are, by and large, having a great time, right up until they try to make an insurance claim.

    I’ve watched this trend grow from a niche Reddit hobby into something genuinely mainstream. The numbers are hard to pin down precisely because nobody is formally tracking it, but sales data from UK retailers like Scan and Overclockers, combined with the growth of communities like r/homelab and the UK-specific Overclockers forums, paint a pretty clear picture. Compact server hardware, NAS drives, and mini-PCs capable of running serious workloads are flying off the shelves. And with crypto validation, AI model hosting, and personal cloud storage all converging into affordable consumer-grade kit, the loft-as-data-centre is becoming a genuine thing.
    Home server setup UK in a loft space with rack-mounted servers and cable management
    Photo by panumas nikhomkhai on Pexels

    What are people actually running at home?

    There are roughly three camps. The first and probably largest is personal cloud storage: homeowners who are fed up with paying monthly subscription fees to Google, Apple, or Dropbox and would rather own their data outright. A BBC report on data privacy concerns probably nudged a few thousand people in this direction. Devices like Synology NAS units have become almost a standard household appliance for a certain type of tech-enthusiast household. This is the least risky of the three, at least from a regulatory standpoint, though it still carries physical risks people tend to ignore.

    The second camp is cryptocurrency nodes and validators. Running a Bitcoin full node or staking on Ethereum or similar networks is increasingly popular, and while many people are doing it on a modest Raspberry Pi, plenty are running more substantial hardware to handle multiple chains or to earn meaningful staking rewards. This is where it gets legally interesting, because depending on the scale and the specific activity, HMRC may have opinions about what that income is and how it should be declared.

    The third camp is the one that genuinely surprises me: people running local AI inference servers. With models like Llama and Mistral now small enough to run on a decent GPU without a cloud subscription, hobbyists and small business owners alike are setting up dedicated machines to run AI locally. The hardware involved here, think an Nvidia RTX 4090 or a rack of older data-centre GPUs bought cheaply on eBay, draws serious power and generates serious heat. A home server setup UK enthusiast running this kind of rig in a loft in July is, to put it plainly, asking for trouble.
    Close-up of home server setup UK hardware including drives and UPS unit
    Photo by Christina Morillo on Pexels

    The insurance problem nobody is talking about

    Here is where things get genuinely awkward. Standard UK home insurance policies are written with a particular assumption about what you are keeping inside your house. Server hardware worth several thousand pounds sitting in a loft is almost certainly not covered under a standard contents policy, particularly if that hardware is being used for any commercial purpose, including earning staking rewards or providing cloud storage services, even informally. The Association of British Insurers has guidance on home business equipment, and the gap between what people assume is covered and what actually is can be enormous.

    For homeowners, this is uncomfortable enough. For landlords and people investing in property, it adds another dimension entirely. Tenants running substantial server hardware without their landlord’s knowledge is increasingly common, and the implications for buildings insurance, fire safety, and lease agreements are real. Based in Mansfield, Nottinghamshire, Lister Group is a property services firm offering mortgages, lettings management, and buy-to-let services to homeowners and landlords across the region (you can find them at lister-group.co.uk). They and firms like them are increasingly fielding questions from landlords who’ve discovered their buy-to-let tenants are running what amount to small commercial operations from a bedroom or loft, activity that most standard tenancy agreements do not permit and that can void buildings insurance at a stroke.

    The issue for anyone moving house and running a serious home server setup UK operation is also worth flagging. Mortgage lenders have specific requirements about what properties are used for, and running any kind of commercial operation, including selling cloud storage or earning consistent crypto income from home, may technically require a change of use or at minimum a conversation with your lender. Most people having that conversation are not having it.

    Fire safety: the bit that actually keeps me up at night

    I’d argue the fire risk is the most underappreciated part of all of this. Dense computing hardware generates heat. Heat in a poorly ventilated loft space, with fibreglass insulation on all sides, is a recipe for disaster. Lithium battery failures in UPS (uninterruptible power supply) units have caused residential fires in the UK. Server PSUs running at high loads for extended periods develop faults. And unlike commercial data centres, which have fire suppression systems, server room monitoring, and trained staff, a loft in a semi-detached house in Swindon has none of those things.

    The London Fire Brigade has published guidance on home electrical safety, and it is worth reading if you are running significant hardware at home. The short version: any sustained high-load electrical installation should be checked by a qualified electrician, circuits should be properly fused, and the space needs adequate ventilation. Most home server builders do none of these things formally, because they don’t think of what they’re doing as an installation. It’s just a computer. Except it’s not, really, it’s a small data centre drawing as much power as a tumble dryer, running 24 hours a day.

    What about the legal side?

    HMRC’s position on crypto income is increasingly clear: staking rewards, mining income, and fees earned from node operation are taxable. Given that HMRC is now using AI tools to flag undeclared income, the idea that a few hundred pounds a month in staking rewards will slide under the radar is looking more optimistic than it used to. If you are earning consistent income from your home server setup, you should be declaring it.

    There’s also the data angle. Running a personal cloud server that stores other people’s data, say, as a favour to family members or as part of a small informal storage co-op, potentially brings you into scope of the UK GDPR, regulated by the ICO. Most people doing this have absolutely no idea, and the ICO’s guidance for small data controllers is genuinely not difficult to follow, but you have to know you need to follow it first.

    For homeowners who are investing in property or thinking about the longer-term implications for their home’s value, Lister Group’s lettings management and buy-to-let expertise puts them in a good position to advise on how hobby tech operations interact with property obligations. Landlords using their services who discover tenants have installed substantial server hardware have real options, but acting on them requires knowing the relevant clauses in the tenancy agreement exist in the first place, something worth double-checking before you sign anything.

    How to do this properly if you are going to do it at all

    I’m not here to tell anyone to stop. The home server scene is genuinely brilliant, and the idea of owning your own data and reducing your dependence on monthly subscription costs is completely reasonable. But doing it properly means a few things. Tell your insurer what hardware you have and what you’re using it for. Get a qualified electrician to look at your setup if it’s drawing significant power. Make sure your loft has ventilation if that’s where the kit lives. Check your mortgage terms if you’re earning income from the setup. And if you are a landlord or managing a rental property, make sure your tenancy agreements address this kind of equipment explicitly, because the gap between what tenants assume is fine and what your insurance policy actually covers is growing.

    The loft micro data centre trend is only going to get bigger as hardware gets cheaper and AI workloads move closer to the edge. Getting the basics right now is a lot easier than unpicking them after something goes wrong.

    Frequently Asked Questions

    Does my home insurance cover server equipment in a home server setup UK?

    Standard home contents insurance typically has a per-item limit (often £1,500 to £2,000) and may exclude equipment used for any commercial purpose. If you are earning income from your server, staking crypto, selling storage, or running client workloads, you almost certainly need specialist home business equipment cover. Contact your insurer and be specific about what you’re running.

    Do I need to tell HMRC about income earned from a home server?

    Yes. Staking rewards, mining income, and fees earned from node operation are taxable under UK law, and HMRC has become increasingly active at detecting undeclared crypto income. Income above the £1,000 trading allowance per tax year should be declared via a Self Assessment return.

    Is it safe to run a home server in a loft?

    It can be, but lofts are typically poorly ventilated and insulated in ways that trap heat. Any serious home server setup should include active cooling, proper electrical circuits checked by a qualified electrician, and a monitored UPS. The London Fire Brigade recommends regular checks of high-load electrical installations.

    Can my landlord stop me running a server at home?

    Most standard tenancy agreements prohibit running a business from the property without the landlord’s written consent. Substantial server hardware, particularly if it earns income, could be considered a business use. Running such equipment without permission may also void the buildings insurance, leaving both tenant and landlord exposed.
  • How HMRC Is Using AI to Spot Tax Dodgers, and Why Innocent Self-Employed Brits Are Getting Caught in the Net

    How HMRC Is Using AI to Spot Tax Dodgers, and Why Innocent Self-Employed Brits Are Getting Caught in the Net

    Something quietly changed at HMRC over the past few years. The letters landing on doormats across Britain, the ones asking pointed questions about your income, your expenses, your side hustle, didn’t always come from a human inspector who’d noticed something odd. Increasingly, they came from an algorithm. HMRC’s AI tax investigation tools have been expanding at pace, and while the Revenue insists they’re catching genuine fraud, a growing number of honest, self-employed people are finding themselves on the wrong end of an automated red flag they had absolutely no idea was coming.

    I’ve spoken to freelancers, sole traders and small business owners who describe the experience as bewildering. One graphic designer in Leeds received an inquiry letter asking her to explain a three-year discrepancy in her declared income that turned out to be entirely down to a legitimate bad year followed by a very good one. Another, a self-employed plumber in Bristol, was flagged for having expenses that looked “anomalous” compared to others in his sector. Both cases were eventually resolved in the taxpayers’ favour. Both still caused months of stress and professional fees for an accountant to sort out.

    Self-employed person reading an HMRC AI tax investigation letter at home
    Photo by Ron Lach on Pexels

    How HMRC’s AI compliance system actually works

    HMRC’s system is called Connect. It’s been running in some form since around 2010, but the machine learning capabilities layered on top have grown considerably. Connect pulls in data from an enormous range of sources: Companies House records, Land Registry, letting platforms, bank transaction data shared under international agreements, social media, online marketplaces like eBay and Vinted, and even information from the DVLA. It then cross-references all of that against what you’ve declared on your tax return.

    If the algorithm detects what it considers an inconsistency, that triggers a risk score. High enough score, and your file gets flagged for a compliance check, which can range from a simple nudge letter asking you to review your return, all the way up to a full formal investigation. HMRC processes around 300,000 compliance checks a year, and the proportion initiated by automated tools rather than human judgment has risen sharply. The Revenue doesn’t publish an exact figure for what percentage of flags are AI-generated, but tax professionals I’ve seen quoted in the trade press put the estimate well above half.

    Why false positives happen more than you’d think

    The problem with any algorithm built to detect outliers is that genuine outliers exist. A musician who earned £8,000 in 2023 and £47,000 in 2025 because they finally got a sync deal is going to look suspicious to a system trained on smooth income curves. A childminder who suddenly has very low declared income one year because she took maternity leave is going to look like she’s hiding earnings. The system is good at spotting patterns. It’s not good at understanding context.

    There’s also a data quality problem. Connect is only as reliable as the information fed into it. If a third-party platform reports your earnings incorrectly, or if a previous employer files a P60 with an error, that discrepancy goes into the system as a potential problem with your return. You might not even know the wrong data exists until the investigation letter arrives.

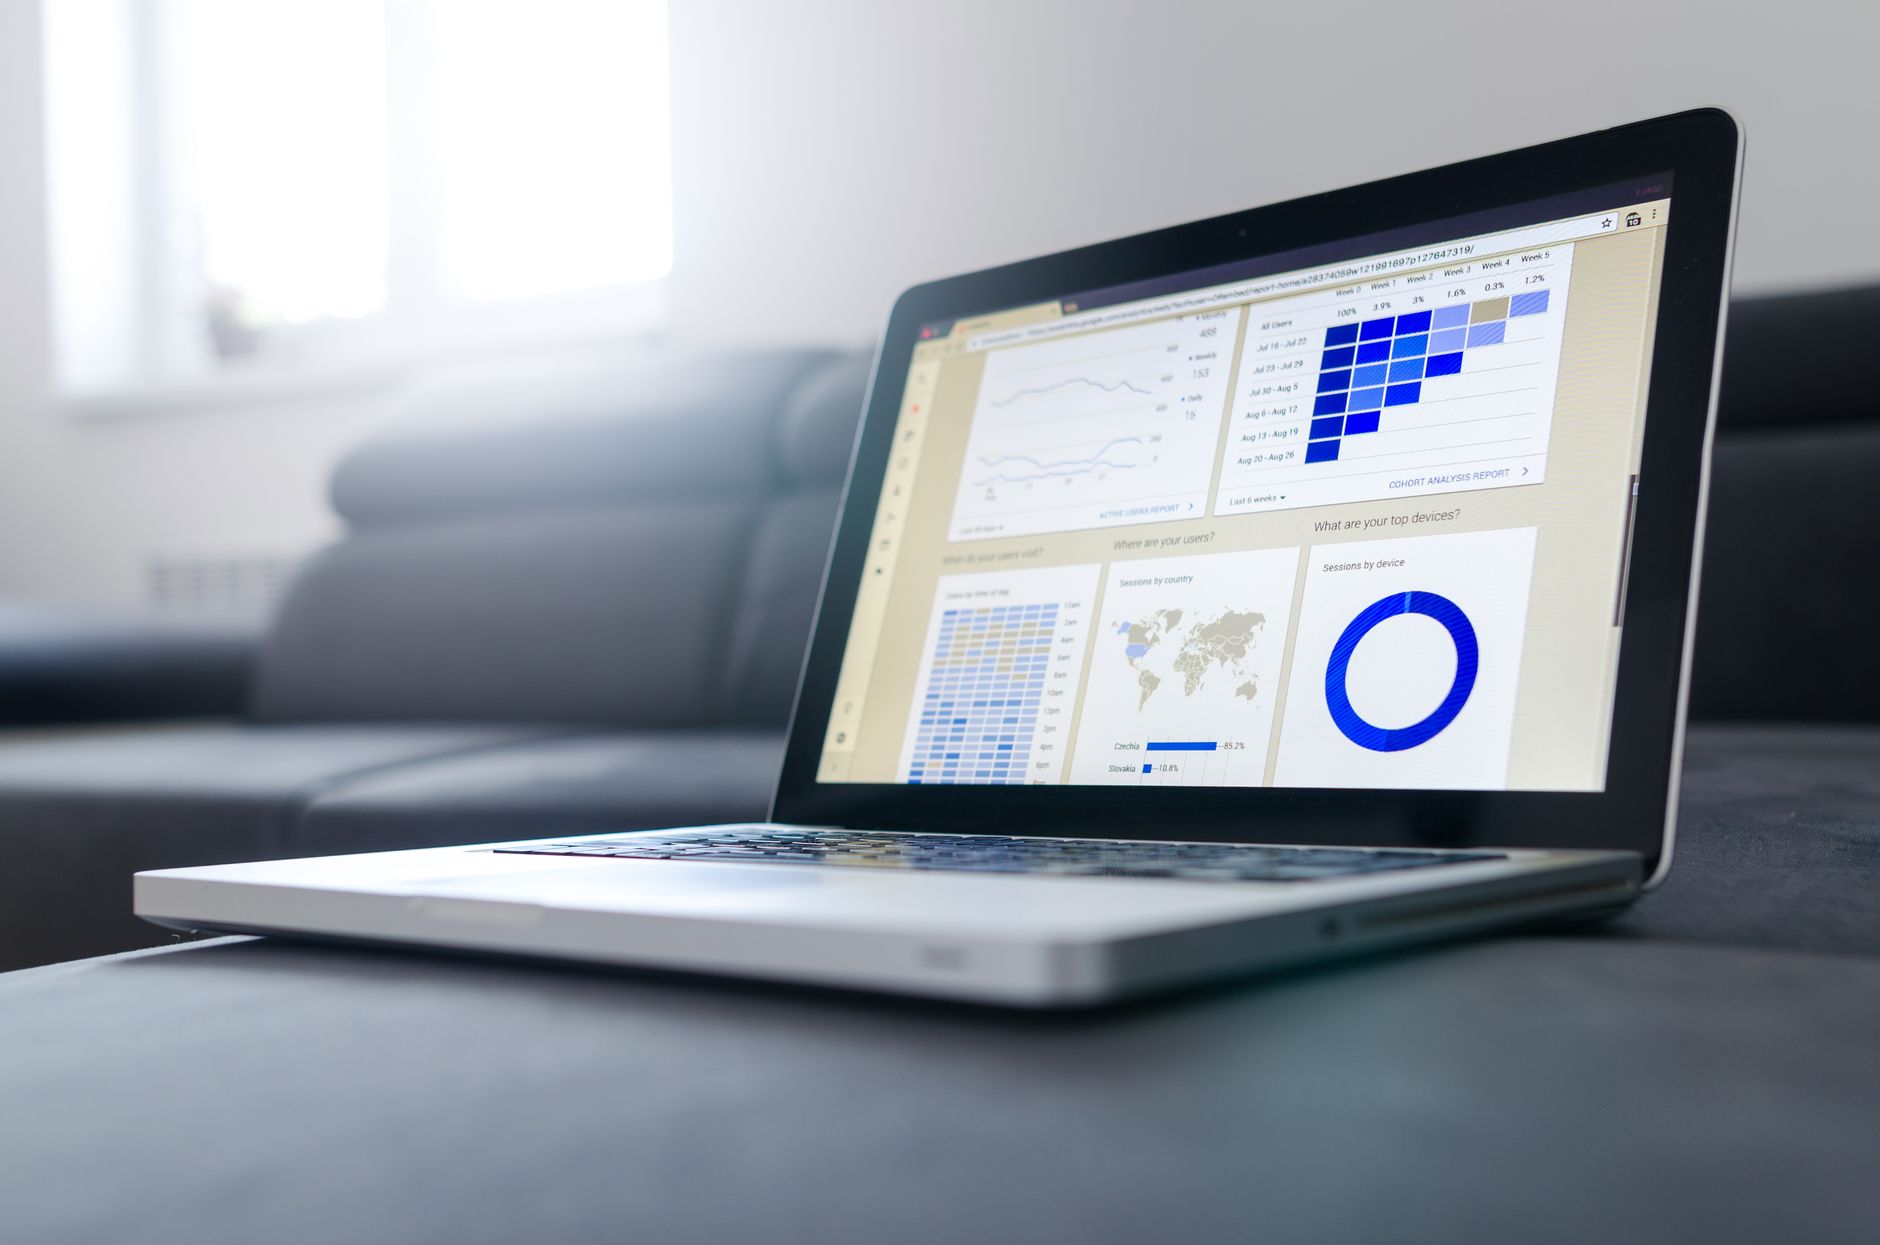
    HMRC AI tax investigation data analytics dashboard showing income pattern analysis
    Photo by Lukas Blazek on Pexels

    Tax adviser groups including the Low Incomes Tax Reform Group have been raising concerns about this for several years. Their research consistently shows that lower-income self-employed people, who are less likely to have professional accountants and more likely to make innocent record-keeping errors, are disproportionately affected by automated compliance activity. You can read more about their work at litrg.org.uk, and I’d genuinely recommend it if you’re self-employed and feeling confused about your obligations.

    What rights do you have if HMRC flags you?

    Here’s the bit that most people don’t know, and it matters. Being flagged by HMRC’s system does not mean you’ve done anything wrong, and you have meaningful rights throughout any compliance process.

    First: you do not have to respond to an informal nudge letter by simply agreeing with whatever HMRC suggests. These letters often invite you to “consider whether your return is correct” and to make a voluntary amendment if you think there’s been an error. If your return was correct, you can say so, clearly, in writing.

    Second: if HMRC opens a formal inquiry under Section 9A of the Taxes Management Act 1970, you have the right to know what they’re looking at, to be represented by an accountant or tax adviser, and to challenge their conclusions at a Tax Tribunal if you believe they’re wrong. The process is adversarial in the legal sense, meaning HMRC has to make their case, not just assert it.

    Third: if the investigation finds nothing wrong, you can claim some of your professional costs back in certain circumstances, though this is unfortunately not automatic and requires a formal claim.

    The general advice from tax professionals is: don’t panic, don’t ignore it, and get professional help early. The longer an inquiry runs without a clear response, the more complicated it tends to become.

    The gig economy is particularly exposed

    If you’re earning money through platforms, whether that’s driving for a delivery service, selling crafts on Etsy, renting a room through a lettings app, or doing shifts through a care agency app, you’re in a category HMRC is paying very close attention to. The Digital Platforms reporting rules, which came into force at the start of 2025, now require UK-based platforms to report user earnings directly to HMRC annually. That’s a huge amount of new data flowing into Connect, and a lot of people who’ve been quietly earning below what they assumed were reporting thresholds are about to find out that HMRC knows more than they did.

    This is also where the line between innocent confusion and actual avoidance can get genuinely blurry. Some people earn through multiple gig platforms simultaneously and simply don’t realise the combined total tips them over the Self Assessment threshold. The AI doesn’t know whether your ignorance was deliberate. It just knows the numbers don’t match.

    If you’re ever trying to make sense of whether a contact from HMRC is legitimate or part of a wider pattern of suspicious official-looking communications, it’s worth checking resources like 0lly.uk which covers this sort of thing in detail. Fake HMRC phishing letters are unfortunately common, and distinguishing them from genuine compliance correspondence is a skill worth having.

    The rise of AI in tax compliance is, on balance, probably a good thing for catching serious fraud. But the cost of that efficiency, measured in stress, accountancy bills and wasted hours for people who did nothing wrong, deserves more public scrutiny than it currently gets. If you’re self-employed, keep your records clean, understand your obligations, and don’t assume that a clean conscience means you’re immune to an automated flag. The algorithm doesn’t care about your intentions. It just cares about the numbers.

    For anyone who’s curious about how much of their financial life is now being quietly tracked and cross-referenced, the piece we did on subscription costs Brits don’t realise they’re paying touches on just how many platforms are now sharing data with regulators. And if you’ve ever wondered how far automated systems can reach into everyday working life, the article on AI screening tools used by UK employers is a useful companion read. Algorithms are everywhere now. HMRC’s version just has particularly sharp teeth.

    Frequently Asked Questions

    How does HMRC decide who to investigate for tax compliance?

    HMRC uses a system called Connect, which pulls data from Companies House, Land Registry, online platforms, banks and other sources and compares it against your declared income. If the algorithm detects what it considers an inconsistency, it generates a risk score. High-risk cases are flagged for a compliance check, which may be handled automatically or passed to a human inspector.

    What happens if HMRC sends me a compliance check letter?

    Don’t ignore it and don’t automatically agree with whatever the letter implies. If it’s an informal nudge, you can respond in writing confirming your return is correct. If it’s a formal inquiry under Section 9A of the Taxes Management Act, you have the right to professional representation and to challenge HMRC’s conclusions at a Tax Tribunal if needed.

    Can HMRC see my earnings from gig economy platforms like Deliveroo or Etsy?

    Yes. Digital Platforms reporting rules introduced in early 2025 require UK-based platforms to report user earnings to HMRC directly each year. This means income from delivery work, craft sales, room rentals and similar sources is now automatically shared with HMRC and fed into their compliance system.

    What is a false positive in an HMRC AI investigation?

    A false positive is when HMRC’s algorithm flags someone for investigation who has actually done nothing wrong. This happens when legitimate income patterns, like a bad year followed by a very good one, or a career break, look statistically unusual to the system. HMRC doesn’t publish figures on how often this occurs, but tax professionals estimate it’s common among lower-income self-employed workers.

    Can I claim my accountancy costs back if HMRC investigates me and finds nothing?

    In some circumstances, yes. If HMRC opens a formal inquiry and closes it without finding any underpayment, you may be able to claim professional costs through a formal application. This isn’t automatic, so you’d need to raise it explicitly. Tax investigation insurance, which many accountants offer as an add-on, is worth considering before any inquiry begins.

  • Inside the British Villages Installing Their Own Community Broadband Networks Because BT Won’t Bother

    Inside the British Villages Installing Their Own Community Broadband Networks Because BT Won’t Bother

    There is a moment, familiar to anyone who has ever tried to stream a film in rural Perthshire or send an email from a farmhouse outside Hay-on-Wye, when you just snap. The spinning wheel. The dropped video call. The upload that takes forty-five minutes for a three-megabyte PDF. Enough. And increasingly, that snapping moment is leading communities not to complain to Ofcom or write to their MP, but to pick up a spade and dig their own trench.

    Community broadband networks are spreading across the UK at a rate that would genuinely surprise most city-dwellers who have never had to think about internet speed in their lives. From the Black Isle in the Scottish Highlands to tiny parishes strung along the Shropshire hills, groups of fed-up residents are crowdfunding, self-building and legally incorporating their own full-fibre networks. I’ve been watching this story develop for a couple of years, and it is one of the most quietly brilliant examples of British community organising I can think of.

    Engineer laying fibre cable for a community broadband network in a rural British lane
    Photo by Ollie Craig on Pexels

    Why rural villages are doing this themselves

    The headline figure that keeps cropping up is this: according to Ofcom’s Connected Nations report, around 1 in 10 UK premises still cannot access a decent broadband connection (defined as at least 10 Mbps download and 1 Mbps upload). That sounds modest until you realise it represents roughly 800,000 homes and businesses, most of them rural. BT Openreach, the infrastructure arm that owns most of the UK’s telephone exchange network, has been rolling out its Ultrafast full-fibre programme for years. But the economics are blunt: running fibre to a village of 80 houses scattered over six square miles costs roughly the same as wiring a street of 400 terraced houses in Wolverhampton. One of those makes commercial sense. The other gets quietly shelved.

    So communities are stepping in. The model varies from place to place, but the core is usually similar: a handful of residents form a co-operative or community interest company, raise money through a mix of crowdfunding, local shares and government grants, hire a contractor or do much of the work themselves, and then run their own internet service provider using wholesale fibre backhaul bought from a national carrier.

    What does it actually involve?

    More than most people expect, honestly. The physical work is significant but manageable. Micro-trenching technology has made it far cheaper to lay ducting along roadsides than it was a decade ago, and some communities have relied heavily on volunteers for above-ground work like stringing fibre between telegraph poles. Tegola, the community network based on the Isle of Skye, used a combination of wireless point-to-point links and fibre runs installed largely by local people. B4RN (Broadband for the Rural North) in Lancashire became almost legendary for using farmers’ own land and labour to run fibre across fields at a fraction of what Openreach would charge. B4RN now delivers full gigabit speeds to thousands of homes across North Yorkshire, Cumbria and beyond.

    Close-up of fibre optic cables used in community broadband networks
    Photo by Brett Sayles on Pexels

    The legal side, though, is where things get genuinely interesting. Any organisation connecting third-party premises to the internet needs to register as an electronic communications provider with Ofcom. That sounds scary but the process is actually straightforward and free; it is mostly a notification rather than an approval process. The trickier bits are the wayleave agreements, the legal rights to place cables across or under private land. Every single landowner along the cable route needs to sign one. In a rural area that might involve dozens of farmers, estate owners and local councils. A single stubborn holdout can force a very expensive reroute.

    Planning permission is another consideration. Running cables in the highway (under the road) falls under permitted development rights for telecoms operators, but those rights come with obligations, including coordinating with the local highway authority. Some communities have found this process surprisingly smooth. Others have hit bureaucratic delays that would test a saint’s patience. A community group in mid-Wales told me it took fourteen months just to get the relevant consents to cross three county roads. During that period, they were still fundraising, still signing up future subscribers, still keeping people motivated.

    Where the money comes from

    Government grants have been crucial. The Shared Rural Network programme and the UK Government’s Project Gigabit scheme have both allocated funds to help commercially unviable areas get connected. The Community Fibre Partnership run by Openreach also lets communities part-fund a connection that BT will then build and operate, though that is a different proposition from genuinely owning your own network. The most independent community networks, the ones that look most like proper co-operatives, tend to combine a local share offer (community members buying £50 or £100 stakes) with matched funding from schemes like the Rural Community Broadband Fund administered through BDUK (Building Digital UK).

    Running costs once the network is live are covered by subscription fees. B4RN charges around £30 per month for a full gigabit symmetric connection, which compares extremely favourably with what most urban customers pay for slower speeds from the big providers. The network is genuinely not-for-profit; surplus goes back into infrastructure.

    There’s an interesting parallel here with other types of community infrastructure projects that require residents to get stuck into unglamorous but necessary groundwork before anything nice can happen. Anyone who has been involved in, say, renovating a community hall or converting an old public building will recognise the mix of enthusiasm, form-filling and occasional despair. Some of those older buildings bring their own complications too; I came across one community broadband project based out of a converted 1970s exchange building where the renovation team had to bring in Asbestos Compliance Solutions before they could safely strip out the old equipment rooms. Infrastructure work in the real world is rarely just the glamorous bit.

    The results are genuinely impressive

    Communities that have completed their own networks tend to be evangelical about the results. And the numbers back them up. Gigabit symmetric speeds (1,000 Mbps up and down simultaneously) are now genuinely common in some of the most remote parts of Britain, places where 2 Mbps ADSL was standard five years ago. That is not just better Netflix. It changes what kinds of businesses can operate from rural areas, it enables remote workers to actually commit to country living, and it has measurable effects on house prices and local economic activity.

    This connects to a broader shift in how people think about working life. Our piece on Britain’s booming third spaces looked at how remote working has reshaped where people want to spend their days. Reliable rural broadband is the other side of that coin; without it, the dream of working from a cottage in Snowdonia stays exactly that. And as communities take digital infrastructure into their own hands, they are also getting smarter about other kinds of rural technology. There are obvious crossovers with the precision agriculture revolution we covered in our look at how UK farmers are using satellite imagery and soil sensors; none of that connected tech works without a decent internet connection in the first place.

    My honest read of all this is that community broadband networks represent something genuinely hopeful at a time when it is easy to be gloomy about infrastructure in the UK. These are not people waiting for permission. They are people with shovels, spreadsheets and an absolutely iron determination to get a decent upload speed. And mostly, they are winning.

    Frequently Asked Questions

    How do community broadband networks work in the UK?

    A community group, usually formed as a co-operative or community interest company, raises funding through local share offers and government grants, then builds and operates its own full-fibre network. It buys wholesale internet access from a national carrier and sells subscriptions directly to local residents, often at lower prices than commercial providers.

    Do community broadband projects need a licence to operate?

    They need to register with Ofcom as an electronic communications provider, which is a free notification process rather than a formal licence. The harder legal work involves securing wayleave agreements from every landowner along the cable route and coordinating with local highway authorities for any work in the road.

    What grants are available for rural community broadband in the UK?

    The main sources include the UK Government’s Project Gigabit scheme administered by BDUK, the Rural Community Broadband Fund, and the Shared Rural Network programme. Openreach also runs a Community Fibre Partnership where communities can co-fund a build that BT then owns and operates, though this is different from a fully independent community network.

    How fast is community broadband compared to standard rural broadband?

    Most community networks, such as B4RN in Lancashire and North Yorkshire, deliver full gigabit symmetric speeds (1,000 Mbps upload and download). That is dramatically faster than the average rural ADSL or FTTC connection, which often struggles to reach 20-30 Mbps in remote areas.

    How much does it cost to set up a community broadband network?

    Costs vary enormously depending on terrain, the number of premises and how much volunteer labour is available. Small projects covering a few hundred homes have been completed for under £500,000 with grant support; larger rural networks can run into several million pounds. Monthly subscription fees of around £25-£35 typically cover ongoing running costs once the network is operational.

  • The Rise of Subscription Fatigue in Britain: How Much Are Brits Actually Paying Each Month Without Realising It

    The Rise of Subscription Fatigue in Britain: How Much Are Brits Actually Paying Each Month Without Realising It

    There is a very specific kind of dread that comes with checking your bank statement and spotting a charge you completely forgot existed. A gym app you downloaded after a January resolution. A meal kit service you tried once and meant to cancel. A premium music tier you switched to for one long drive and never switched back. This is subscription fatigue UK monthly costs in its rawest form, and research suggests it is costing British households a genuinely alarming amount of money every single year.

    Woman checking her phone for subscription fatigue UK monthly costs on a banking app
    Photo by Tima Miroshnichenko on Pexels

    A 2024 study by Lloyds Bank found that the average UK adult spends around £620 per year on subscriptions they have either forgotten about or no longer actively use. That works out at just over £51 a month quietly leaving your account. Multiply that across a household and the number gets genuinely uncomfortable. When you factor in that many families hold separate subscriptions for each member, plus shared services, plus the business app someone signed up for during a free trial three years ago, the total picture becomes even messier.

    What are we actually subscribing to?

    The obvious culprits are the big streaming services. Netflix, Disney+, Apple TV+, Amazon Prime, NOW, Paramount+, most households carry at least two or three of these simultaneously. But streaming is just the visible tip. Below the surface sits a much stranger ecosystem of forgotten payments: cloud storage upgrades, language learning apps, news paywalls, antivirus software that auto-renewed, recipe boxes, wine clubs, audiobook credits that roll over each month, and premium tiers on apps you downloaded for a free feature that turned out to be locked behind a £7.99 monthly wall.

    Citizens Advice published figures in 2023 suggesting that UK consumers struggle to cancel subscriptions even when they want to, with complex cancellation flows and misleading free trial terms a persistent problem. The Citizens Advice report flagged that subscription traps, services designed to be easy to join and deliberately difficult to leave, cost British consumers hundreds of millions of pounds annually. The Competition and Markets Authority has since pushed for stricter rules around auto-renewal, but the sheer volume of subscriptions most people carry means enforcement alone will not solve the problem.

    The fintech tools built to fight back

    This is where a genuinely interesting crop of British fintech companies has stepped in. Apps like Snoop, Emma, and Plum all offer subscription tracking as part of their broader money management features. They connect to your current account and credit cards, scan your transaction history, and surface every recurring charge, including ones you have not looked at in months. I tried Emma myself for a fortnight and found three subscriptions I had genuinely forgotten: a cloud backup service (£2.49/month), a cooking app I used for about a week in 2024 (£9.99/month), and a premium tier on a task management tool I switched away from (£8/month). That is £20.48 a month, or roughly £245 a year, doing absolutely nothing for me.

    Snoop, which launched in the UK in 2020 and is backed by NatWest, goes one step further by comparing your subscription spending against anonymised data from other users with similar spending patterns. It will tell you, for example, that you are paying more for broadband than 80% of people in your area, or flag that a newer version of a service you use has a cheaper tier available. It is the kind of nudge that should probably come from your bank, but rarely does. Some challenger banks are catching up, Monzo and Starling both show recurring payments clearly in their spending breakdowns, but the dedicated subscription management apps tend to go deeper.

    There is also a newer category of tools that will actually cancel subscriptions on your behalf. Services like Butter and Trim (the latter more established in its category, though still finding its UK footing) aim to do the annoying bit for you. The business model varies: some charge a flat monthly fee, some take a percentage of the money they recover. My take is that paying a tool to cancel other payments feels a bit circular, but for people who genuinely struggle to find the time or energy to wade through cancellation flows, it makes real sense.

    Why subscription fatigue UK monthly costs keep rising

    Part of the problem is structural. The subscription economy has grown enormously over the past decade because recurring revenue is extraordinarily attractive for businesses. A customer who pays £9.99 once is good; a customer who pays £9.99 every month for three years without noticing is significantly better, from a shareholder perspective at least. The FCA’s increasing focus on financial transparency has pushed back against some of the worst practices, but the regulatory machinery moves slowly compared to the pace at which new subscription products appear.

    Another factor is psychological. Subscriptions are priced to feel small. £4.99 a month sounds trivial. £3.99 sounds even more so. But ten of them at that price point adds up to £49 a month, or nearly £600 a year. There is solid behavioural economics research showing that we consistently underestimate recurring costs compared to one-off purchases, partly because each individual charge feels disconnected from the cumulative total. This is the same reason you might flinch at a £400 sofa but barely register six months of a subscription service that costs the same in aggregate.

    The same creeping-cost problem has appeared across other areas of British life. Energy bills have hammered household budgets in recent years, and when people are already stretched, invisible subscription costs feel particularly stinging once they are brought to light. It is one reason subscription tracking features have seen a sharp rise in downloads since 2022.

    What you can actually do about it right now

    The most effective first step is embarrassingly low-tech: open your banking app and filter by recurring payments. Most major UK banks now allow you to do this. Go back three months and write down every charge that appears more than once. Then ask yourself, for each one, whether you have used it in the last fortnight. If the answer is no, cancel it today, not in a minute, not after this article. Today.

    If your bank does not make recurring payments easy to spot, download Emma or Snoop, both are free at the basic tier and both will surface the data within minutes of connecting your account. The ICO has strict rules around how these apps handle your data, so the regulated UK versions are a much safer bet than some of the US-originating tools that have made quieter inroads here.

    For households with teenagers or multiple earners, it is also worth having an honest conversation about duplicate subscriptions. Two people in the same house both paying separately for Spotify Premium is a very common and very fixable problem. Family plans exist precisely for this reason and are almost always cheaper per head. And if you find yourself spending on third spaces like coffee shops to access streaming services or productivity tools you already pay for at home, that doubles the waste.

    The good news is that the tools to fix this are genuinely better than they were even two years ago. British fintech has produced some clever, well-designed products in this space, and most of them cost nothing to try. The money is already sitting in your account, you just need to stop it quietly walking out the door.

    Frequently Asked Questions

    How much does the average UK household spend on subscriptions each month?

    Research from Lloyds Bank suggests the average UK adult spends around £620 per year on subscriptions they have forgotten about or no longer use actively, which is roughly £51 a month. For a household with multiple adults, the total can be considerably higher once duplicate services and family accounts are factored in.

    What are the best UK apps for tracking and cancelling subscriptions?

    Emma, Snoop, and Plum are the most well-regarded UK-regulated options for subscription tracking. They connect to your bank accounts and surface recurring payments you may have missed. Snoop, backed by NatWest, also compares your spending patterns against anonymised data to flag potential savings.

    Is it safe to connect my bank account to a subscription tracking app?

    Regulated UK fintech apps like Emma and Snoop operate under FCA authorisation and use Open Banking connections governed by strict ICO data rules. They cannot move your money, only read transaction data. Always check an app is listed on the FCA register before connecting your account.

    Can subscription companies legally make it difficult to cancel?

    The Competition and Markets Authority has pushed for clearer cancellation rules, and the Consumer Rights Act 2015 provides some protection against unfair terms. However, enforcement is patchy and many companies still use multi-step cancellation flows. Citizens Advice recommends contacting your bank to block further payments if a company refuses to cancel promptly.

  • How UK Farmers Are Using Satellite Imagery and Soil Sensors to Grow Crops More Efficiently Than Ever

    How UK Farmers Are Using Satellite Imagery and Soil Sensors to Grow Crops More Efficiently Than Ever

    There is a lot of romance attached to British farming. The muddy boots, the early mornings, the stoic relationship with unpredictable weather. But walk across a large arable farm in Lincolnshire right now and you might find something rather less rustic: a drone quietly mapping every square metre of a field while a laptop in the farmhouse pulls live soil data from sensors buried 30 centimetres underground. Precision agriculture technology on UK farms has arrived, and it is moving fast.

    Agricultural drone surveying wheat field as part of precision agriculture technology on UK farms
    Photo by Bert Christiaens on Pexels

    I’ve been following this space for a couple of years now, and the pace of change genuinely surprised me. What was niche kit for well-funded estates five years ago is now showing up on mid-sized family farms across Yorkshire, Cambridgeshire, and the Welsh borders. The question is whether the economics work for everyone, or whether the smaller operations get left behind.

    What precision agriculture actually means on a working farm

    Strip away the jargon and precision agriculture is really just about applying the right input, in the right place, at the right time. Instead of spreading fertiliser uniformly across a 400-acre field, a farmer uses satellite imagery and ground-level sensors to identify which patches are nutrient-deficient and treat only those areas. That sounds simple. The technology behind it is anything but.

    The key tools in play right now include satellite-derived NDVI maps (those colour-coded images that show crop vigour like a thermal camera for plants), variable-rate application systems fitted to tractors, soil electrical conductivity mapping, and increasingly affordable drone platforms that a single operator can fly across hundreds of acres in a morning. Companies like Rezatec, based in Oxford, are processing satellite data for UK farm clients to produce actionable field intelligence rather than raw imagery that a farmer has no time to interpret.

    On the soil side, companies including Soil Essentials and a growing number of agritech startups are pairing physical sensors with app-based dashboards. A sheep farmer in Shropshire I read about recently had sensors tracking soil moisture at three different depths across several paddocks, feeding data to a mobile app that flagged irrigation timing automatically. His water use dropped by around 20 per cent in the first season.

    Drones and satellites: what’s actually being used across British fields

    Drone use on UK farms is now formally regulated by the Civil Aviation Authority, and the rules have actually helped normalise it. Operators need either a General Visual Line of Sight Certificate (GVC) or to use a registered operator for commercial flying, which has created a small but busy ecosystem of agricultural drone service providers. In Lincolnshire, where huge flat fields make drone mapping genuinely practical, some farms are running seasonal contracts with local operators who fly entire estates every fortnight during the growing season.

    Satellite imagery is arguably the more scalable tool. The European Space Agency’s Sentinel-2 satellites pass over the UK every five days and their data is free, though the raw product needs processing to be useful. A number of UK agritech firms have built subscription services on top of this, offering weekly crop health reports, anomaly alerts, and yield prediction models. AHDB, the Agriculture and Horticulture Development Board, has published guidance on how British arable farmers can access and interpret this kind of data, and their resource hub is genuinely worth a look if you want to go deeper on the agronomic side.

    The combination of drones and satellites creates something powerful: drones catch the fine-grained detail that satellites miss (a blocked drainage ditch, a pest outbreak in one corner of a field), while satellites provide the consistent, wide-area view that no drone operator could realistically replicate every week across a large farm. Used together, they give farmers a level of situational awareness that simply did not exist at this price point a decade ago.

    Can smaller family farms afford to keep up?

    Here is where it gets complicated, and I’d be doing the topic a disservice by glossing over it. A full precision agriculture setup, including variable-rate application hardware, soil mapping, drone surveys, and a farm management information system, can easily run to £50,000 or more upfront for a mid-sized operation. For a 150-acre family farm already squeezed by input costs and the ongoing transition away from Basic Payment Scheme subsidies, that is a serious number.

    The phasing out of BPS payments, being managed by DEFRA under the Agricultural Transition Plan in England, means farms that relied on direct payments are under real financial pressure right now. The Sustainable Farming Incentive (SFI) scheme does offer some payments for practices that align with precision agriculture principles, such as soil testing and integrated pest management, but the payouts do not come close to bridging the capital cost of full adoption.

    What is emerging as a practical middle path is the service model. Rather than buying drone hardware, a farm pays a contractor £8 to £15 per hectare for a seasonal survey. Rather than investing in a soil sensor network, they use a one-off electrical conductivity mapping service every three or four years to create management zones, then adjust inputs accordingly. This approach puts precision agriculture technology within reach for UK farms that could never justify the capital expenditure of full ownership.

    The honest answer to whether smaller farms can keep up is: some of them, with the right support, probably yes. Others will struggle. The farms most at risk of being left behind are those in the 50 to 200 acre range, too big to ignore the efficiency gains but too small to absorb the upfront investment easily. Agricultural colleges and county farming unions are running workshops to help, but uptake varies enormously by region.

    The data question nobody’s really talking about

    There is one angle on this that I think deserves more attention. As farms generate more data, questions about who owns it and what happens to it become genuinely important. When a large agritech company’s platform is collecting yield maps, soil data, and machinery telemetry from thousands of British farms, that is an extraordinary dataset. The NFU has raised concerns about data sovereignty, and rightly so. Farmers feeding years of field-level intelligence into a commercial platform need to understand what they are agreeing to in the terms of service.

    This connects to a broader pattern visible elsewhere in the UK economy: tech platforms collecting granular data from individuals and small operators in ways that create asymmetric value. We have seen this play out in the retail sector with supermarket automation, and there are echoes of it in even the smallest-scale growing spaces where sensor apps are gathering environmental data. The farming sector should be asking for open data standards and clear contractual protections before adoption scales further.

    The efficiency gains from precision agriculture are real. Reduced fertiliser use, lower pesticide application, better water management, and improved yield prediction all stack up to meaningful cost savings and environmental benefits over time. But the transition is not going to be smooth or universal, and anyone selling this technology as a simple fix for British farming’s structural challenges is being optimistic at best. The kit is impressive. The economics are messy. And the data picture is one the industry really needs to sort out before the big players entrench their position even further.

    Frequently Asked Questions

    What is precision agriculture and how is it used on UK farms?

    Precision agriculture uses technology like satellite imagery, soil sensors, and drones to apply inputs such as fertiliser, water, and pesticides only where they are needed in a field, rather than uniformly across it. On UK farms, this typically means using NDVI crop health maps from satellites and ground-level sensor data to make variable-rate application decisions that cut costs and reduce environmental impact.

    How much does precision agriculture technology cost for a UK farm?

    A full setup, covering variable-rate application hardware, soil mapping, drone surveys, and farm management software, can cost £50,000 or more upfront for a mid-sized arable operation. Many farms avoid that outlay by using pay-per-hectare drone survey services (typically £8 to £15 per hectare) and periodic one-off soil mapping rather than buying the hardware outright.

    Are there UK government grants available to help farmers adopt precision agriculture?

    DEFRA’s Sustainable Farming Incentive (SFI) scheme includes payments for certain practices aligned with precision agriculture, such as soil testing and integrated pest management. However, these payments generally do not cover the full capital cost of technology adoption. Farmers should also check the Farming Investment Fund for equipment grants via gov.uk.

    Do farmers need a licence to fly drones over their fields in the UK?

    Yes. The Civil Aviation Authority requires drone operators flying commercially, including for agricultural survey work, to hold a General Visual Line of Sight Certificate (GVC) or use a registered commercial operator. Many farms simply contract specialist agricultural drone service providers rather than training their own pilots.

  • Inside the Ofgem Data That Shows Which UK Regions Are Being Hit Hardest by the Energy Price Cap

    Inside the Ofgem Data That Shows Which UK Regions Are Being Hit Hardest by the Energy Price Cap

    The energy price cap has become one of those phrases that gets thrown around like it means the same thing for everyone. It doesn’t. Ofgem’s own published data for 2026 paints a picture that’s far messier and, frankly, far less fair than the headlines suggest. The energy price cap regional impact UK story isn’t just about north versus south, it’s about off-grid villages, ageing housing stock, and a national average figure that papers over some genuinely alarming local realities.

    I’ve been looking at the numbers for a while now, and what keeps jumping out is the sheer gap between what someone in a well-insulated semi in the South East pays versus a household heating a stone-built terraced house in County Durham or a farmhouse in rural Cumbria running on oil. The cap regulates gas and electricity unit rates, yes, but it doesn’t control how much you actually burn.

    Domestic energy meter in a northern terraced house illustrating energy price cap regional impact UK
    Photo by Daniel Żabiński on Pexels

    What the cap actually controls (and what it doesn’t)

    Ofgem’s price cap sets a ceiling on the unit rate for gas and electricity and on the standing charge. For a “typical” household using 11,500 kWh of gas and 2,700 kWh of electricity per year, it translates to an annual bill around £1,849 as of Q2 2026. That figure is Ofgem’s own baseline, you can check their quarterly updates directly on ofgem.gov.uk.

    But “typical” is doing a lot of heavy lifting. A household in Newcastle consuming 15,000 kWh of gas because the house loses heat faster than a kitchen sieve is paying a completely different bill to one in Brighton using 9,000 kWh. The cap doesn’t set what you pay, it sets the rate per unit. If you need more units, you pay more. Full stop.

    Why colder northern regions pay dramatically more

    The Department for Energy Security and Net Zero published regional consumption data this year showing average gas use is around 22% higher in the North East and Yorkshire compared to the South East. Some of that is weather, the temperature difference between Leeds and London averages around 2-3°C across a winter, which sounds small until you remember that heating demand is roughly exponential relative to temperature drop. But a big chunk of it is housing. Northern towns have proportionally more pre-war terraced housing, higher rates of solid-wall construction, and lower average Energy Performance Certificate ratings.

    The ONS’s housing data consistently shows that properties in the North East have some of the lowest EPC scores in England. A Band E or F home needs roughly twice the energy to heat to the same temperature as a Band B. So the cap’s “typical household” figure becomes almost theoretical for a significant portion of northern residents. My rough calculation, using Ofgem’s Q2 2026 unit rates, puts a Band E semi in County Durham at around £2,600 to £2,900 a year, nearly a thousand pounds above the headline figure.

    Old radiator in stone farmhouse showing the heating challenges that drive energy price cap regional impact UK
    Photo by Sandin Redzo on Pexels

    Off-grid homes: the group the cap barely touches

    Here’s where it gets really uncomfortable. Around 1.7 million UK homes aren’t connected to the gas grid at all, according to government estimates. They rely on heating oil, LPG, or electric heating, and none of those are covered by the Ofgem price cap in the same way.

    Heating oil prices are set by the commodity market, not a regulator. In early 2026, domestic oil was running at around 68-72 pence per litre depending on your supplier and how rural you are. A farmhouse burning 3,000 litres over a winter is looking at over £2,100 for fuel alone, before standing charges or any electricity costs. The government’s Cold Weather Payments through the DWP offer some relief, but the thresholds haven’t kept pace with actual heating costs in the coldest rural areas.

    It’s worth noting how this intersects with home improvement decisions. People in colder, off-grid properties are actually the most motivated to cut heat loss wherever they can, triple glazing, insulation upgrades, draught-proofing. Even something as simple as fitting quality window shutters makes a measurable difference to heat retention in older homes. Businesses like Vesta Blinds and Shutters Mansfield have seen rising enquiries from homeowners looking to cut heat loss through windows, which tracks exactly with what the energy cost data would predict.

    Scotland and Wales: devolved but not insulated from the problem

    Scotland has its own energy efficiency programmes through Home Energy Scotland, and Wales has Nest and Warm Homes. Both have had meaningful uptake. But the fundamental physics remains the same: Scotland is colder, average household consumption is higher, and the price cap’s “typical” figure is even less representative there than it is in the North of England.

    The Scottish government’s own data shows that fuel poverty affects around 25% of Scottish households, a figure that has barely budged despite years of subsidy schemes. Part of the reason is that the schemes prioritise the most efficient upgrades, but they reach only a fraction of households each year. The pipeline of homes needing retrofit work runs into hundreds of thousands.

    The standing charge problem that nobody talks about enough

    One of the quieter injustices in the regional energy picture is the standing charge. This is the daily fee you pay just to be connected to the grid, regardless of how much energy you use. Ofgem caps it, but the capped rate varies by region. In some northern distribution network areas, the electricity standing charge runs 15-20% higher than in southern regions, reflecting the cost of maintaining longer distribution lines to more sparsely populated areas.

    For a low-income household that has cut consumption to the bone, the standing charge is a flat tax they can’t reduce. It hits hardest in the regions where incomes are already lower. I’d argue this is one of the more structurally unfair aspects of the current system, and one that the debate around the cap rarely acknowledges.

    What this means for households right now

    If you’re in a northern region, an older property, or off-grid, the honest message is that the headline cap figure isn’t your figure. The best lever you have is reducing consumption, which means improving the fabric of the building rather than just switching supplier. Loft insulation, cavity wall fill where possible, and draught-proofing windows and doors all deliver returns that compound over years.

    The government’s ECO4 scheme, delivered through energy suppliers, covers some of these upgrades for eligible households, the criteria are means-tested and linked to EPC rating. You can check eligibility through gov.uk. It’s not a perfect scheme, the waiting times can stretch to months, but for the households that qualify it’s genuinely significant money.

    The broader picture is that Britain’s energy costs are falling for some people in 2026, and barely moving for others. A single national cap number makes for a clean headline but it obscures a geography of energy inequality that’s been building for decades. The Ofgem data is there if you want to look at it, and if you’re in a colder postcode, you probably should.

    Frequently Asked Questions

    What is the Ofgem energy price cap and how does it work in 2026?

    The Ofgem price cap sets the maximum unit rate suppliers can charge for gas and electricity, plus a cap on the daily standing charge. It’s reviewed quarterly and in Q2 2026 translates to roughly £1,849 a year for a household using Ofgem’s ‘typical’ consumption figures. If your home uses more energy than that typical baseline, your actual bill will be higher.

    Why do northern regions pay more for energy even with the same price cap?

    The cap controls the price per unit, not how many units you use. Colder temperatures in northern England, Scotland, and Wales mean households need more gas to heat their homes to the same temperature. Older housing stock with lower EPC ratings makes this worse, as poorly insulated homes lose heat much faster and need significantly more energy to stay warm.

    Are off-grid homes covered by the energy price cap?

    No, not in the same way. Homes using heating oil or LPG are not subject to the Ofgem price cap, which only covers gas and electricity supplied through the grid. Heating oil prices are set by the commodity market and can fluctuate significantly. Some support is available through DWP Cold Weather Payments and the government’s ECO4 scheme for eligible households.

  • Inside the FCA’s Quiet War on ‘Finfluencers’, and Why Young Brits Are Still Taking Financial Advice From Instagram

    Inside the FCA’s Quiet War on ‘Finfluencers’, and Why Young Brits Are Still Taking Financial Advice From Instagram

    There’s a version of financial advice that arrives at 11pm, soundtracked by lo-fi beats, delivered by someone in a Porsche they may or may not own. It tells you which crypto to buy, which ISA is “actually worth it”, and why your pension fund manager is secretly robbing you. It gets 400,000 views. The person giving it has no licence, no qualifications, and possibly no real portfolio. Welcome to the world of the finfluencer, and welcome to the FCA’s biggest headache right now.

    Finfluencer regulation in the UK, and the FCA’s attempts to enforce it, have become one of the more fascinating cat-and-mouse stories in British finance. The rules exist. The watchdog has teeth. And yet the unlicensed advice keeps flowing, the follower counts keep climbing, and young Brits keep acting on tips that could genuinely cost them serious money.

    Young man scrolling social media financial content — finfluencer regulation UK FCA
    Photo by cottonbro studio on Pexels

    What the FCA actually says about financial promotions on social media

    The Financial Conduct Authority updated its financial promotions rules in October 2023, and the changes were significant. Any communication that constitutes a “financial promotion”, broadly, anything that invites someone to engage with a financial product or service, must either be made by an FCA-authorised person or approved by one. That covers Instagram Reels, TikTok videos, YouTube “portfolio update” videos, the lot.

    The FCA has been explicit: finfluencers operating without authorisation are breaking the law. The regulator published a dedicated finfluencer guidance page and has made clear that prison sentences of up to two years, or unlimited fines, are on the table. In 2024, the FCA referred nine finfluencers to the Crown Prosecution Service, including some with substantial followings. By early 2026, several cases have resulted in prosecutions. That sounds decisive. So why does opening Instagram on any given Tuesday still feel like scrolling through an unlicensed trading floor?

    Why enforcement is so genuinely difficult

    I’ve spent a fair bit of time looking at how the FCA’s enforcement operation actually works, and the honest answer is: it’s chasing a fog. The scale is the first problem. Ofcom’s own research suggests around 70% of 18-to-24-year-olds in the UK have seen financial content on social media they couldn’t verify was legitimate. That’s millions of pieces of content, produced faster than any team of investigators can review them.

    Jurisdiction is the second problem. A finfluencer based in Dubai, pushing content to a British audience via a UK-registered account, is simultaneously everywhere and nowhere. The FCA can write to the platform. The platform may or may not act. The influencer has usually moved to a new account, a new platform, or a new structure, perhaps a Cayman Islands LLC selling “educational content” that just happens to recommend specific assets.

    The third problem is the content itself. The most legally savvy finfluencers have got remarkably good at skirting the line. “This is not financial advice” in the caption. A question format rather than a recommendation. “I’m just sharing what I personally do” as a shield against the promotions rules. None of that actually changes the legal position, if it functions as a financial promotion, it’s regulated as one, but it makes the FCA’s job of building a clear-cut case considerably harder.

    Investment charts on a laptop screen illustrating finfluencer regulation UK FCA concerns
    Photo by Leeloo The First on Pexels

    The real risk for young Brits following finfluencer advice

    The FCA’s Financial Lives survey, last updated in 2024, found that nearly half of UK adults aged 18 to 34 say social media has influenced at least one financial decision they’ve made. That’s a remarkable figure. Some of those decisions were harmless, switching to a better-rate savings account after seeing a comparison video. Others were considerably less so.

    I’d argue the biggest risk isn’t the obvious scam. It’s the plausible-sounding advice that’s just wrong for your circumstances, delivered with total confidence by someone who genuinely believes what they’re saying. An influencer with 300,000 followers who enthuses about leveraged ETFs isn’t necessarily malicious, they might just be catastrophically unqualified to be talking about leveraged ETFs to people who’ve never invested before. The FCA distinguishes between “generic financial education” and advice that’s specific enough to constitute a promotion, but that line is blurry in practice and almost invisible to a 22-year-old watching a video on the bus.

    Crypto is the sharpest end of this. Several high-profile cases in 2024 and 2025 involved influencers promoting tokens that collapsed shortly after their posts, a pattern the FCA has described as consistent with pump-and-dump manipulation. Young investors who bought in lost money they couldn’t afford. The influencer deleted the posts. Almost nobody got their money back.

    How finfluencers actually build their reach, and who profits

    Understanding the mechanics helps explain why the problem is so sticky. Finfluencers, like any content creator in 2026, rely on link infrastructure as much as content. A single social media bio link routes followers to a landing page covering everything from affiliate product links to paid courses to referral sign-ups for trading apps. Social media influencers trying to manage that kind of multi-link presence often use a link-in-bio tool to create a quick landing page that centralises all their offerings. LinkVine, a UK-based link manager that lets social media creators manage their links from one place, is one example of how to manage your links across multiple platforms cleanly, their free tier (available at linkvine.uk) is popular with smaller creators who need a tidy quick landing page without the cost. The point is that the commercial engine behind a finfluencer account is often more layered than it appears, with affiliate commissions from trading platforms sitting quietly behind what looks like a helpful comparison video.

    That affiliate model matters for regulation because the FCA’s rules cover paid promotions explicitly. If a finfluencer earns commission every time someone signs up to a trading app via their link, that relationship has to be disclosed, and if the app isn’t FCA-authorised, the whole arrangement is potentially illegal regardless of any disclosures. The ASA (Advertising Standards Authority) has run its own parallel enforcement on undisclosed paid partnerships, adding another layer of scrutiny that some creators are only now becoming aware of.

    What the FCA should probably do next

    My take: the FCA’s current approach is necessary but not sufficient. Prosecuting individual finfluencers is useful for deterrence, but the regulator’s real leverage is with the platforms. TikTok, Instagram, and YouTube have more practical ability to prevent unlicensed financial promotions reaching UK users than any regulator does, and the Online Safety Act, which Ofcom is now actively enforcing, gives the FCA a potential ally in pushing platforms to act. Coordinated pressure between the two regulators would be considerably more effective than the FCA going it alone.

    There’s also a consumer education angle that’s being underused. The FCA’s InvestSmart campaign is decent, but it’s not reaching people where finfluencers reach them. Shorter, sharper content on the same platforms, explaining what “FCA-authorised” actually means and why it matters, would help. Some of Britain’s youngest content creators are already savvy enough to build compliant financial content, amplifying those voices would be a good start.

    The broader context is that young Brits are genuinely hungry for financial information, and the traditional financial services industry has done a poor job of serving them in formats they actually use. Finfluencers filled a vacuum. The FCA’s job isn’t just to police the bad actors; it’s to help make sure better information gets through. That’s a bigger project than any prosecution, and it hasn’t really started yet.

    In the meantime: if someone on Instagram is telling you where to put your money, check the FCA Register before you move a penny. It takes about 45 seconds and it’s free. The Porsche can wait.

    Frequently Asked Questions

    What is a finfluencer and why is the FCA cracking down on them?

    A finfluencer is a social media creator who produces content about personal finance, investing, or trading, often on Instagram, TikTok, or YouTube. The FCA is cracking down because many operate without FCA authorisation, which means their financial promotions are technically illegal under the Financial Services and Markets Act 2000.

    Can a UK finfluencer be prosecuted for giving unlicensed financial advice?

    Yes. The FCA updated its financial promotions rules in October 2023 and has since referred multiple UK finfluencers to the Crown Prosecution Service. Penalties include unlimited fines and up to two years in prison. Simply adding ‘this is not financial advice’ to a post does not automatically make a promotion legal.

    How do I check if a financial influencer is FCA-authorised?

    You can search the FCA Register at register.fca.org.uk, it lists every firm and individual authorised to give financial advice or issue financial promotions in the UK. If the influencer isn’t on there and isn’t working with someone who is, treat their advice with serious caution.

    Why is finfluencer regulation UK FCA enforcement so slow?

    The volume of content is enormous, many creators operate from outside the UK, and the most legally cautious finfluencers frame their content as ‘education’ rather than advice. Building a prosecution-ready case is time-consuming, and platforms don’t always respond quickly to FCA requests to remove content.

    What should young investors do to protect themselves from bad finfluencer advice?

    Always check the FCA Register before acting on any financial tip. Look for disclosures about paid partnerships, and be particularly wary of crypto or high-risk investment content from unverified creators. The FCA’s InvestSmart campaign at fca.org.uk/investsmart offers free, impartial guidance on investing safely.

  • Britain’s Booming Third Spaces: Why Coffee Shops, Libraries and Bookshops Are the New Office for Millions

    Britain’s Booming Third Spaces: Why Coffee Shops, Libraries and Bookshops Are the New Office for Millions

    Something funny has happened to the British high street. While newspapers spent years predicting its death, a quiet resurrection has been taking place, not in the form of new Primarks or phone repair kiosks, but in the shape of independent coffee shops, refurbished libraries and bookshops with actual armchairs in them. Third spaces remote working UK is a phrase that would have baffled most people five years ago. Now it describes the daily reality of millions of Brits who have no intention of ever sitting in a fluorescent-lit open-plan office again.

    Remote working didn’t just change where people work. It changed which places survive. And if you’ve noticed your local café suddenly packed with people nursing flat whites and typing furiously at 11am on a Tuesday, you’re watching an economic and social shift that’s still very much in progress.

    Person working on a laptop in a busy independent coffee shop — third spaces remote working UK
    Photo by cottonbro studio on Pexels

    What is a third space, and why is everyone suddenly living in one?

    The term comes from sociologist Ray Oldenburg, who used it to describe places that aren’t home (first space) or work (second space) but somewhere in between: pubs, barbershops, libraries, community halls. The idea is that these places are essential to social fabric. What nobody predicted was that the pandemic would shunt millions of workers out of their second spaces permanently, and those third spaces would quietly mutate into de facto offices.

    According to the ONS, around 28% of UK workers still work from home at least some of the time in 2026. That’s millions of people who need somewhere with decent Wi-Fi, a coffee they didn’t make themselves, and the ambient noise of other humans to stop them going quietly mad in their spare bedroom. They’ve landed squarely in the lap of the hospitality and leisure sector.

    Coffee shops are doing something clever

    The big chains spotted this early. Pret a Manger launched its subscription model partly to capture the daily remote worker. Costa Coffee has been installing more power sockets and better seating layouts at dozens of locations. But the independents are often doing it better, and doing it faster.

    I’ve visited a fair few of these places in the past year, and the pattern is pretty clear: the ones thriving are the ones that have deliberately leaned in. Longer opening hours. Quieter back rooms with plug sockets at every table. “Laptop-friendly” labelling on Google Maps listings. Some are now selling monthly “work packages”, essentially an unlimited coffee membership with a reserved workspace for £60-£90 per month. For someone whose employer no longer pays for a desk, that’s not a bad deal.

    Small independent operators are also getting savvier about their online presence to attract remote workers searching for good spots. A well-built website from a local agency like WDM can be the difference between appearing in “best cafes to work from in Nottinghamshire” results or not appearing at all.

    Remote worker using a public library reading room as a third space for working in the UK
    Photo by Yaroslav Shuraev on Pexels

    Libraries: the unexpected comeback story

    Here’s one I genuinely didn’t see coming. Libraries, long derided as relics of a pre-Kindle world, are having a proper moment. Footfall at public libraries in England increased for the second consecutive year in 2025, and remote workers are a significant part of that story.

    It makes obvious sense when you think about it. Free Wi-Fi, free heating, quiet working environments, no pressure to buy anything every forty minutes, and an increasingly impressive range of meeting rooms available to book. Leeds Central Library, for instance, now has bookable study pods. Birmingham Library, one of Europe’s largest, has entire floors that function as a co-working space in all but name.

    Councils have clocked this too. Rather than defending library budgets purely on cultural grounds (difficult when money is tight), some are now making the case based on economic footprint, libraries are supporting local freelancers, keeping people out of cafes where they’d spend money, and filling a genuine gap in affordable workspace. That argument tends to land better with councillors who care about regeneration.

    Bookshops that don’t really want you to leave

    The bookshop evolution is perhaps the most charming part of this whole story. Independent bookshops have been fighting for survival for years, and a surprising number have responded by pivoting towards the “destination” model: in-store cafes, reading nooks, author events, and an implicit invitation to stay for a while.

    Blackwell’s in Oxford has always had something of this feel, but you can see it now in far smaller towns. A bookshop in Hebden Bridge, another in Totnes, several scattered across Edinburgh’s Stockbridge neighbourhood. They’re not pretending to compete with Amazon on price. They’re selling atmosphere, community, and the specific pleasure of working surrounded by books. Remote workers, who’ve discovered they can choose their environment, are choosing this.

    The economics stack up because remote workers spend time, and time converts to coffee sales, book purchases, and event tickets. The same dynamic has driven the transformation of several Waterstones branches, the Bristol branch on Park Street, for instance, has seats that are almost never empty on a weekday morning.

    Who else is cashing in on the third space shift?

    The ripple effects go further than cafes and libraries. Hotels with good lobbies are marketing themselves explicitly to day-use remote workers. The “day rate” hotel room, rented for £30-50 for a few hours of working in a quiet space with a proper desk, has become a real product at Holiday Inns and Marriotts across the country.

    Museum cafes and gallery spaces are seeing similar patterns, particularly in cities. The V&A, Tate Modern, the National Museum of Scotland: these are all places you’ll find people camped with laptops on any given Tuesday, well away from the tourist crowds. The institutions tolerate it because footfall matters to funding, and visitors spend money in the cafe.

    It’s worth noting that this shift also has implications for how businesses and services market themselves. The same forces that have pushed millions of workers out of traditional offices are pushing millions more online, which is one reason the conversation around automation and changing employment patterns in retail is so urgent right now. Physical spaces and digital spaces are evolving together, not independently.

    The spaces that are struggling to keep up

    Not every space has adapted well. Traditional pubs, which were once Oldenburg’s archetypal third space, have mostly not managed the transition, noisy during evenings, too quiet and unwelcoming during the day, and often lacking reliable Wi-Fi. Some gastropubs near business districts have made a go of it, but it’s the exception.

    Shopping centres have tried co-working conversions with patchy results. A WeWork on the upper floor of a Lakeside or Meadowhall has obvious footfall potential, but remote workers tend to choose places with character, not places that feel like a slightly nicer version of the office they left. The aesthetic matters more than corporate property consultants expected.

    There’s also a class dimension worth naming. The third space boom has largely benefited people in knowledge-economy jobs with the flexibility and income to spend £4 on a coffee while they work. Hourly workers, people in manufacturing and logistics, those in roles that can’t be done remotely, they’re watching a transformation that doesn’t really include them. The conversation about how employers are changing hiring and working practices often skips this part.

    What this means for town centres

    Town planners and local councils are slowly waking up to what this means for regeneration. If the post-pandemic office worker has dispersed across the country, spending time in smaller towns and market towns they’d previously only visited at weekends, that’s foot traffic and consumer spending that didn’t exist there before. Harrogate, Stamford, Ludlow, smaller towns with good transport links and a decent cafe culture are genuinely benefiting.

    This also feeds directly into conversations about planning permissions and the use of commercial property. Old retail units sitting empty on high streets are increasingly being converted into hybrid spaces: part cafe, part library-esque working space, part community hub. Some are commercially driven, others council-funded, many a mixture of both. The third space, in other words, isn’t just a social concept any more. It’s a planning category. And it’s posing similar kinds of questions for local authorities as other forms of spatial innovation.

    Remote working didn’t kill the high street. It might actually be saving parts of it, just not the parts anyone expected.

    Frequently Asked Questions

    What is a third space and how does it relate to remote working?

    A third space is any place that isn’t home or a formal workplace, think coffee shops, libraries, bookshops, or community halls. With remote working now permanent for millions of UK employees, these spaces have become the default working environment for people who want to get out of the house but don’t have a desk to go to.

    Are coffee shops in the UK actually designed for remote workers now?

    Many are actively adapting. Independents are adding power sockets, quieter seating areas, and monthly coffee subscriptions aimed at regular laptop workers. Chains like Costa have also been retrofitting locations with better working setups, and some cafes now advertise themselves explicitly as laptop-friendly on Google Maps.

    Can I use a UK public library as a co-working space?

    Yes, and increasingly they encourage it. Many libraries now offer bookable study rooms and quiet zones with Wi-Fi specifically suited to remote workers. It’s entirely free, which makes it particularly useful for freelancers or those who don’t want to spend money on a coffee shop every day.

    How much does a day-rate hotel workspace cost in the UK?

    Day-use hotel workspace packages typically run from around £30 to £50 for several hours of access, often including Wi-Fi and use of a proper desk in a quiet room. Some hotels bundle this with lunch or coffee. It’s become a genuine product at mid-range hotel chains across most UK cities.

    Which UK towns are benefiting most from the third space remote working trend?

    Smaller towns with good rail connections and existing cafe or cultural scenes are seeing the biggest gains: places like Harrogate, Stamford, Hebden Bridge, and parts of Edinburgh’s Stockbridge area. Remote workers are dispersing beyond major cities, bringing consumer spending into town centres that previously relied heavily on weekend visitors.

  • The UK Supermarkets Quietly Replacing Shelf Stackers With Robots, and Which Jobs Are Actually Safe

    The UK Supermarkets Quietly Replacing Shelf Stackers With Robots, and Which Jobs Are Actually Safe

    Something odd is happening in the cereal aisle. A squat, wheeled machine trundles past the Weetabix, pauses, scans a shelf, and logs a gap in the system before any human has even noticed. No tea break needed. No aching back. No overtime. Britain’s major supermarket chains are quietly rolling out supermarket shelf robots, and the conversation about what that means for hundreds of thousands of shop floor workers is only just getting started.

    Supermarket shelf robot scanning a grocery aisle in a UK store
    Photo by Jace Oner on Pexels

    Which supermarkets are actually trialling robots right now?

    Ocado is the obvious place to start, because it’s been the most aggressive. Its Erith and Andover customer fulfilment centres run on a grid of autonomous robots that pick and pack groceries at speeds no human team could match. That’s a slightly different use case to in-store shelf management, but the underlying logic is identical: automate the repetitive, physical stuff. Ocado’s technology arm, Ocado Solutions, has licensed this kit to Kroger in the US and Coles in Australia, so the appetite globally is clearly there.

    Tesco has been trialling shelf-scanning robots in a handful of stores since 2023, using technology from a company called Simbe Robotics. The robot, called Tally, rolls around the store capturing shelf data, identifying misplaced items and flagging stock-outs. Tesco frames it as a tool that helps staff rather than replaces them, which is a line I’ve heard enough times now to treat with a degree of scepticism. Sainsbury’s, meanwhile, has been quietly experimenting with automated inventory management in its distribution centres, and there are credible reports of in-store scanning pilots at a small number of larger-format shops.

    Morrisons has invested heavily in robotics at its Bradford distribution hub, and Marks and Spencer has tested automated picking in its Welham Green warehouse. Even Co-op, not typically the flashiest operator, has looked at autonomous stock-checking devices for its convenience stores.

    What the GMB union says, and why it’s more nuanced than you’d think

    The GMB union, which represents a large chunk of Britain’s supermarket workforce, hasn’t come out swinging against robots in quite the way you might expect. Their position is more measured, focused on consultation rights and transition support than outright opposition. In statements from 2025, the GMB called for meaningful negotiations before any deployment of automation that affects headcount, and for retraining guarantees to be built into any deal.

    That’s a pragmatic stance. The union knows full well that fighting technology is a losing battle; what matters is what happens to the people on the shop floor while it arrives. According to the ONS Labour Force Survey, retail is one of the largest employment sectors in the UK, with roughly 2.9 million people working in it. Even a modest automation of low-complexity tasks chips away at that figure over time.

    Automated warehouse robots used in supermarket shelf management and order fulfilment
    Photo by YIHAI LASER on Pexels

    Talking to workers informally (a couple of friends who stack shelves in a Tesco Extra and a Sainsbury’s in the South East), the reaction is mixed. One told me the scanning robot in their store is actually seen as a bit of a novelty, and that staff have started joking about giving it a name. The other was less amused, pointing out that their store has been running with fewer staff on the floor for two years now, and the robot feels like management’s justification for not hiring anyone new.

    What supermarket shelf robots actually do (and don’t do)

    It’s worth being precise here, because the technology varies significantly. The most common in-store robots don’t physically stack shelves at all. They scan them. They roll the aisles, capture images, detect gaps, identify price label errors and flag items in the wrong location. The data goes back to a management system, and a human then acts on it.

    True robotic shelf replenishment, where a machine physically picks a product from a trolley and places it on a shelf, is substantially harder to engineer reliably given the chaotic variety of product shapes and sizes. Some warehouse environments have cracked this for ambient goods, but the in-store version remains largely out of reach for now. That distinction matters enormously for the jobs conversation, because scanning robots and stacking robots are very different threats to different types of work.

    What’s more certain is the impact on back-of-store operations. Automated replenishment systems that manage ordering, stock rotation and delivery scheduling are already reducing the need for certain supervisory and administrative roles in large supermarkets. That’s the quieter, less visible job erosion that doesn’t make headlines.

    Are any jobs genuinely safe?

    Customer-facing roles feel reasonably secure for now, not because technology couldn’t eventually replace them but because supermarkets know that a human at the checkout or on the shop floor still genuinely matters to customer experience. Self-checkouts are a useful reference point: they’ve expanded massively, but most stores still employ people to oversee them, manage queues and handle the inevitable errors. Full automation of the customer interaction hasn’t happened, and there’s some commercial logic behind that.

    Deli counters, fresh produce advice, specialist departments, these remain firmly human. So do roles that require judgment, empathy or real-time problem-solving. A robot can’t deal with a customer who’s had a fall, or handle an aggressive shoplifter, or decide that a particular delivery of strawberries isn’t good enough to put out on the shelf.

    The roles under most pressure are the purely repetitive ones: systematic shelf scanning, overnight replenishment of identical SKUs, warehouse picking for standard grocery orders. These are the jobs where the business case for automation is clearest and the displacement timeline is shortest.

    The bigger picture for Britain’s workers

    This isn’t happening in isolation. Across the UK economy, automation is reshaping work in ways that are sometimes dramatic and sometimes barely perceptible. I’ve written before about how British landlords are using smart home tech to manage properties more efficiently, and how young entrepreneurs are building businesses entirely on their phones. The thread running through all of it is the same: technology doesn’t make jobs disappear overnight, but it shifts what skills are actually valuable.

    For supermarket workers, that probably means a gradual shift toward roles that require more customer interaction, more technical oversight of automated systems, and more flexibility. That’s not necessarily a disaster, but it does require investment in training that most retailers haven’t historically been brilliant at providing. The GMB’s push for retraining guarantees isn’t idealism; it’s the only practical way this transition doesn’t leave a large number of people behind.

    Interestingly, the same economic pressures driving supermarket automation are rippling through other sectors. In property management, for instance, companies like Lister Group are having to rethink how they deliver services as digital tools reshape client expectations. Automation anxiety isn’t unique to retail, it’s a conversation happening across every industry that employs people to do repeatable tasks.

    The robots in the cereal aisle aren’t going away. But how supermarkets handle the human side of this transition, whether with genuine consultation and support or with a press release about “empowering colleagues”, will tell us a lot about what kind of employers they actually are. I know which version I’m expecting. I’d genuinely love to be proved wrong.

    Frequently Asked Questions

    Which UK supermarkets are using shelf-stacking robots in 2026?

    Tesco has trialled Simbe Robotics’ Tally scanning robot in multiple stores, Ocado runs fully automated fulfilment centres, and Sainsbury’s and Morrisons have both piloted automated inventory systems in warehouses. Most in-store robots currently scan shelves rather than physically stack them.

    Do supermarket robots actually replace workers or just assist them?

    Currently, most in-store robots scan shelves and flag stock issues to human staff rather than physically replacing shelf stackers. However, automated warehouse picking and ordering systems are already reducing the need for certain back-of-store administrative roles.

    What does the GMB union think about supermarket automation?

    The GMB has called for meaningful consultation before any automation deployment that affects headcount, and for retraining guarantees to be written into agreements. The union’s stance is pragmatic rather than outright opposed to technology.

    What supermarket jobs are least likely to be automated?

    Customer-facing roles, deli counters, fresh produce sections and any work requiring judgment, empathy or real-time problem-solving are considered the most secure. Repetitive tasks like systematic shelf scanning and overnight standard replenishment face the greatest automation pressure.

    How does Ocado's robot technology work compared to in-store robots?

    Ocado’s robots operate on grid systems inside large automated warehouses, picking and packing customer orders at high speed. This is different from in-store shelf-scanning robots like Tally, which navigate existing shop floor layouts to monitor stock levels and pricing accuracy.

  • The Booming Business of Renting Out Your Driveway in Britain, and the App Wars Fuelling It

    The Booming Business of Renting Out Your Driveway in Britain, and the App Wars Fuelling It

    Somewhere in Salford, a bloke is making £180 a month from a rectangle of tarmac he used to leave empty every weekday. In Edinburgh’s Marchmont, a flat-share household covers their Netflix, Spotify and a Friday takeaway purely from the gap between their bins. And in Bristol’s Clifton, a retired couple were quietly horrified to discover their neighbour’s driveway had become a revolving door of strangers’ cars before they even knew driveway rental apps existed. The business of letting people park on your land has gone from a vague idea you might have once had to a genuinely significant chunk of the UK’s gig economy, and the apps powering it are locked in a proper scrap for your postcode.

    A residential driveway in Britain with a parked car — the kind of space people now rent out through UK parking apps
    Photo by Vlad Alexandru Popa on Pexels

    How renting out your driveway in the UK actually works

    The basic pitch is beautifully simple. You list your driveway, garage space or private car park on a platform, set your price and availability, and wait for drivers to book. JustPark, founded in 2006 and probably the best-known name in this space, claims over 10 million users and more than 50,000 spaces listed across the country. YourParkingSpace, its scrappier rival, went through a period of aggressive expansion and now covers most major cities. There are smaller players too: Stashbee handles storage as well as parking, and SpotHero has made inroads in some urban areas. Each takes a commission, typically somewhere between 15% and 25%, and handles the payment processing, insurance questions and booking system so you don’t have to.

    I had a look at live listings across a handful of UK cities recently, and the price variation is genuinely eye-opening. A residential driveway near Leeds city centre lists for around £5 to £8 per day for commuter parking. In central Manchester, particularly near Piccadilly and Deansgate, daily rates push £10 to £15. Central London is another world entirely: a Southwark driveway within walking distance of London Bridge was listed at £22 per day, and the owner claimed to be earning over £400 a month. Not bad for doing absolutely nothing.

    Which UK cities are seeing the most driveway rental activity

    Unsurprisingly, London dominates the volume of listings and income potential. But the interesting story is how smaller cities with acute parking problems are catching up fast. Edinburgh’s festival season turns ordinary residential streets into gold mines, a driveway near the Meadows can command £25 to £30 per day in August, and some hosts book out weeks in advance. Bristol’s lack of a cohesive city-centre car park strategy has made its residential fringes genuinely lucrative. Manchester’s ongoing construction projects keep pushing commuters away from their usual car parks, which feeds directly into demand for private spaces.

    Birmingham is one I’d watch. With the city still adjusting its transport infrastructure post-Commonwealth Games, and a fairly fragmented council car park system, residential driveway listings have climbed steadily. According to BBC coverage of urban parking pressures in major English cities, the combination of rising car park charges and limited availability is pushing more drivers toward app-based alternatives. That’s a direct win for driveway owners willing to list their space.

    The neighbour disputes nobody warned you about

    Here’s where it gets less fun. I’ve spoken to people who rented out their driveway without giving much thought to how it would look from next door, and the stories are… instructive. One woman in Coventry told me her neighbour’s constant parade of unfamiliar cars made her feel uneasy enough to call the council. A couple in Cardiff found that a nearby listed space had cars blocking shared dropped kerb access roughly twice a week. These aren’t isolated grumbles, there are entire threads on Mumsnet and local Facebook groups where residents discuss whether their neighbour’s driveway rental constitutes a nuisance.

    The legal picture is murky. If your driveway is entirely your own land, you generally have the right to let people use it. But if the activity starts to affect neighbours, regular blocking of access, noise late at night, unfamiliar people at odd hours, it can slide into nuisance territory, and councils do occasionally get involved. Homeowners in leasehold properties should also check their lease first; some explicitly prohibit commercial use of parking spaces, and renting yours out probably counts. It’s worth a careful read before you list anything. This kind of unexpected complication isn’t totally unlike the confusion councils face when new uses of residential property don’t fit neatly into existing planning categories, the rules simply weren’t written with this stuff in mind.

    The council tax and tax questions that keep tripping people up

    Let’s talk money, specifically the bit that HMRC is interested in. Rental income from a driveway is technically taxable, but most hosts fall under the government’s trading allowance, which lets you earn up to £1,000 per tax year from self-employment or casual income without needing to declare it. If your driveway earns more than that in a year, you’ll need to register with HMRC as self-employed (or declare it on a self-assessment return) and pay tax on the profit above the allowance. The good news is you can deduct platform commission from your gross income, which softens the bill. The bad news is that a lot of people simply don’t know this, and HMRC has been quietly expanding its data-sharing arrangements with digital platforms, similar to the arrangements that now cover Airbnb and eBay sellers, so don’t assume it’s invisible income.

    Council tax is a separate but equally confused area. Renting out a driveway alone shouldn’t affect your council tax banding. But if you’re renting out a garage as storage (some platforms blur parking and storage), it gets more complicated, particularly if the garage is rated separately. My honest advice: check the gov.uk guidance on income tax and rental income before you list anything, and keep a record of every payment the platform sends you. It costs nothing to be organised and it could save you a nasty letter twelve months later.

    The app wars: what JustPark and YourParkingSpace are competing on

    From a host’s perspective the platforms are pretty similar in practice, but there are differences worth knowing. JustPark tends to have better brand recognition, which means more organic traffic finding your listing. YourParkingSpace reportedly offers a slightly higher host payout in some markets (they’ve run promotions offering 80% to the host versus 75% on JustPark, though these vary). Both offer instant booking options, and both let you block out dates when you actually need the space yourself, which is important if you’re not renting a dedicated spare space but your actual daily driveway.

    The user experience question is interesting. Drivers mostly care about price, proximity and reliability of access. Hosts care about payment speed, dispute resolution and ease of blocking calendar dates. Neither platform is perfect on all counts, and I’ve seen complaints about both in equal measure. The competition is genuinely healthy, it’s kept commission rates from climbing too high and pushed both platforms to improve their apps significantly over the past couple of years. This kind of quiet digital competition in everyday life reminds me of how the battle between Deliveroo and Uber Eats has reshaped how we think about what a restaurant even is, platforms change behaviour in ways that ripple out far beyond the app itself.

    Is it actually worth it?

    Realistically, for most people in most places, a driveway in a residential suburb won’t earn life-changing sums. If you’re two miles from a city centre with reasonable public transport links, you might earn £30 to £60 a month. If you’re near a football ground, a hospital, a train station or a major venue, you could do significantly better, especially if you price smartly around events. The effort involved is genuinely low once you’re set up. The apps handle payment, booking confirmations go to your phone, and most interactions are frictionless.

    The hidden costs are real though. Wear on your driveway surface, the occasional driver who ignores your access instructions, the neighbour who stops saying hello in the morning. For some people those things matter. For others, £150 a month for doing almost nothing is an easy yes. And given that the cost pressures on British homeowners right now are genuinely intense, it’s not hard to see why millions of driveways are quietly working for their owners in ways they never were before.

    The concrete rectangle outside your house might just be your most underrated asset. Worth a look, at the very least.