Two houses. Same street. Same number of bedrooms. One gets insurance quoted at £400 a year, the other at £620. One gets callbacks from employers, the other gets quietly passed over. The only difference? A couple of letters and numbers at the end of the address. UK postcode house prices, and the broader life-altering power of postcodes in general, are one of those subjects that sounds slightly paranoid until you actually look at the numbers. Then it sounds completely reasonable to be mildly obsessed with it.
I’ve spent a fair bit of time poking around Rightmove data and regional property reports, and the gaps between postcode districts are genuinely staggering in places. This isn’t just a London thing either, though London does serve up some of the most dramatic examples on the planet. Manchester and Edinburgh both have their own postcode quirks that are worth paying attention to, especially if you’re thinking about buying or renting anywhere near a district boundary.
How much difference does a postcode actually make to house prices?
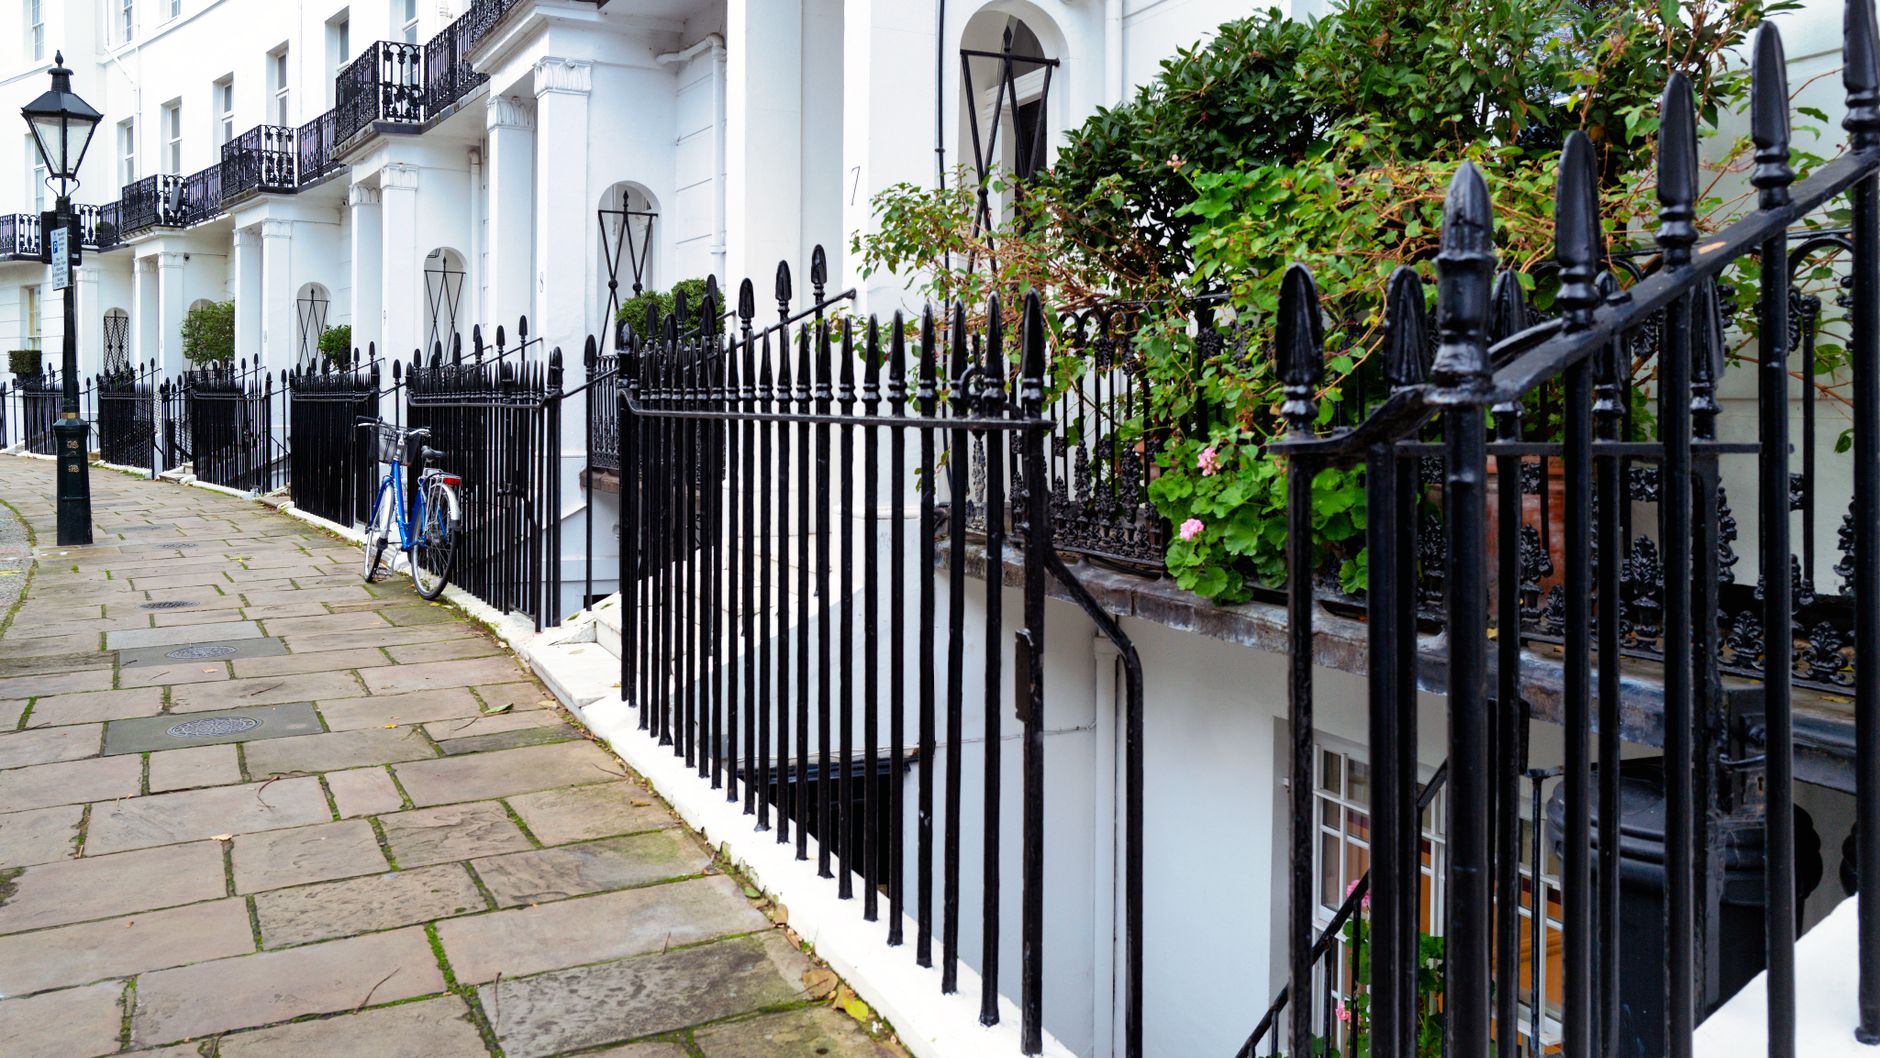
In London, the difference between adjacent postcode districts can be £100,000 or more for comparable properties. SW3 (Chelsea) has an average property price well above £1.5 million, while a ten-minute walk into SW10 (West Brompton) drops that average considerably. Cross into SW6 (Fulham) and you’re in different territory again. Rightmove’s own data consistently shows that buyers pay a premium for certain two-letter and one-number combinations that, in isolation, mean nothing whatsoever.
Manchester tells a similar story, just with different numbers. M20 (Didsbury) regularly clocks average prices 30-40% higher than M14 (Fallowfield), despite being genuinely close to each other. Both have similar housing stock in parts. Both are south of the city centre. But M20 carries a reputation, and that reputation is priced in. Estate agents in that area will tell you, off the record, that they’ve seen buyers specifically request properties on the M20 side of a road when the boundary runs down the middle of a street.
Edinburgh’s postcode effect is slightly different because the city’s geography is more compact. EH3 covers the New Town area and carries prices that reflect its Georgian architecture and proximity to Princes Street. EH6 (Leith) has been creeping up fast since regeneration kicked in properly, and there’s genuine debate now about whether Leith’s postcode stigma is finally fading. I’d argue it mostly has, but older data still drags down average comparisons when you look at aggregated figures.
Insurance premiums and the postcode lottery nobody talks about enough
Home and car insurance pricing by postcode is one of those things that the industry talks about openly but the public mostly doesn’t realise is happening at this granularity. Insurers use postcode-level claims data, flood risk mapping, crime statistics, and even proximity to fire stations to price policies. The result is that two people with identical cars and identical driving records can pay wildly different premiums based purely on where they park at night.
The Association of British Insurers has published guidance on this, and the Financial Conduct Authority reviewed the practice as part of its broader pricing fairness work in recent years. But it remains entirely legal and extremely widespread. Some postcodes in parts of Birmingham, Bradford, and east London carry premiums that are double those of adjacent districts. You could technically save hundreds of pounds on your car insurance by moving a mile down the road, if the move crosses the right boundary.
Flood risk is a particularly sharp edge here. Postcodes in flood-risk zones, as mapped by the Environment Agency, face buildings insurance premiums that can make mortgage lenders nervous. Some insurers simply won’t quote for certain postcodes without specialist cover. This feeds directly back into property values, because a house that’s difficult or expensive to insure is a house that’s harder to sell.
Job applications: the postcode bias nobody wants to admit
This one surprised me when I first came across the research. There’s been credible academic work suggesting that job application callback rates vary by the postcode listed on a CV, even when all other factors are identical. The Social Mobility Commission has referenced geographic inequality in hiring outcomes, and several UK universities have run audit studies using matched CVs sent to the same employers with only the address changed.
The effect is subtle but real. Addresses in areas associated with deprivation, or in postcodes that carry social stigma, get fewer callbacks in some industries, particularly finance and professional services. It’s not as dramatic as the race or gender gaps that have been documented, but it’s there. Some recruiters deny it strenuously. Others, when pressed in off-the-record conversations, admit that a London postcode from E6 versus EC1 can create an unconscious impression before the CV is even properly read.
Schools in high-value postcodes obviously benefit from this dynamic too. Parents who can afford to choose where they live often pick specifically to access school catchment areas, which then feeds back into property prices in a cycle that planners and policymakers find difficult to break. Organisations working on this, like R2G.co.uk, are looking at systemic ways to give schools across all postcodes better outcomes, which is exactly the kind of work that needs to happen if postcode luck is going to matter less in a child’s life.
The strangest postcode stories from around the UK
There are streets in London where the road itself sits on a district boundary, meaning houses on the left side of the street have a different postcode to houses on the right. Estate agents have reported buyers specifically requesting one side over the other. In some cases, the price difference between a left-side and right-side property on the same street runs to tens of thousands of pounds for no physical reason whatsoever.
W1 is arguably the most financially powerful postcode prefix in the country, covering Mayfair, Marylebone, and parts of Soho. Businesses pay a premium just to have it on their letterhead, and some companies that operate from outer postcodes actually rent virtual office addresses in W1 purely for the impression it creates. This connects to a broader pattern I’ve written about before with ghost brands and the way UK businesses manage perceptions far beyond what’s physically real.
In Manchester, the M2 postcode covers a very small slice of the city centre but carries a weight that’s entirely disproportionate to its size. Similarly, EH1 in Edinburgh is geographically tiny but covers the Royal Mile and the Old Town, making it one of the most recognisable postcodes in Scotland.
Can you actually game the postcode system?
Technically, yes, in limited ways. Giving a different address to an insurer to get a cheaper quote is fraud, so don’t do that. But genuinely moving to a slightly different area, or choosing between two properties on either side of a district boundary with full knowledge of what that means for your premiums and resale value, is just sensible information-gathering.
Property buyers who understand this tend to look very carefully at where district boundaries fall. If you can get into M20 rather than M14, or EH3 rather than EH6, for the same budget, you’re buying into a different projected trajectory for your property’s value. It’s not guaranteed, neighbourhoods change, but historically the premium postcodes have maintained their premiums.
The postcode system itself, a relic of Royal Mail routing logic dating back to the 1950s and 60s, was never designed to carry this much social and economic weight. But here we are. Two letters, a number, a space, and then three more characters. And somehow that string of information can shape your insurance bill, your job prospects, your children’s school options, and whether your house is worth £200,000 or £450,000. Absolutely wild, when you think about it.
Frequently Asked Questions
Which UK postcode has the highest average house prices?
Historically, W1K in London (covering parts of Mayfair) has recorded some of the highest average property prices in the UK, often exceeding several million pounds. SW3 (Chelsea) and SW7 (South Kensington) also consistently rank near the top according to Rightmove’s annual data.
Do insurance companies really charge more based on your postcode?
Yes, entirely legally. Insurers use postcode-level data on crime rates, flood risk, accident frequency, and claims history to calculate premiums for both home and car insurance. Moving to a lower-risk postcode can sometimes save hundreds of pounds a year on your policy.
Can a postcode affect your job application chances?
Research and audit studies in the UK have found subtle callback rate differences based on the address listed on CVs, particularly in professional services roles in cities like London. The Social Mobility Commission has flagged geographic bias in hiring as part of broader socioeconomic inequality in the job market.